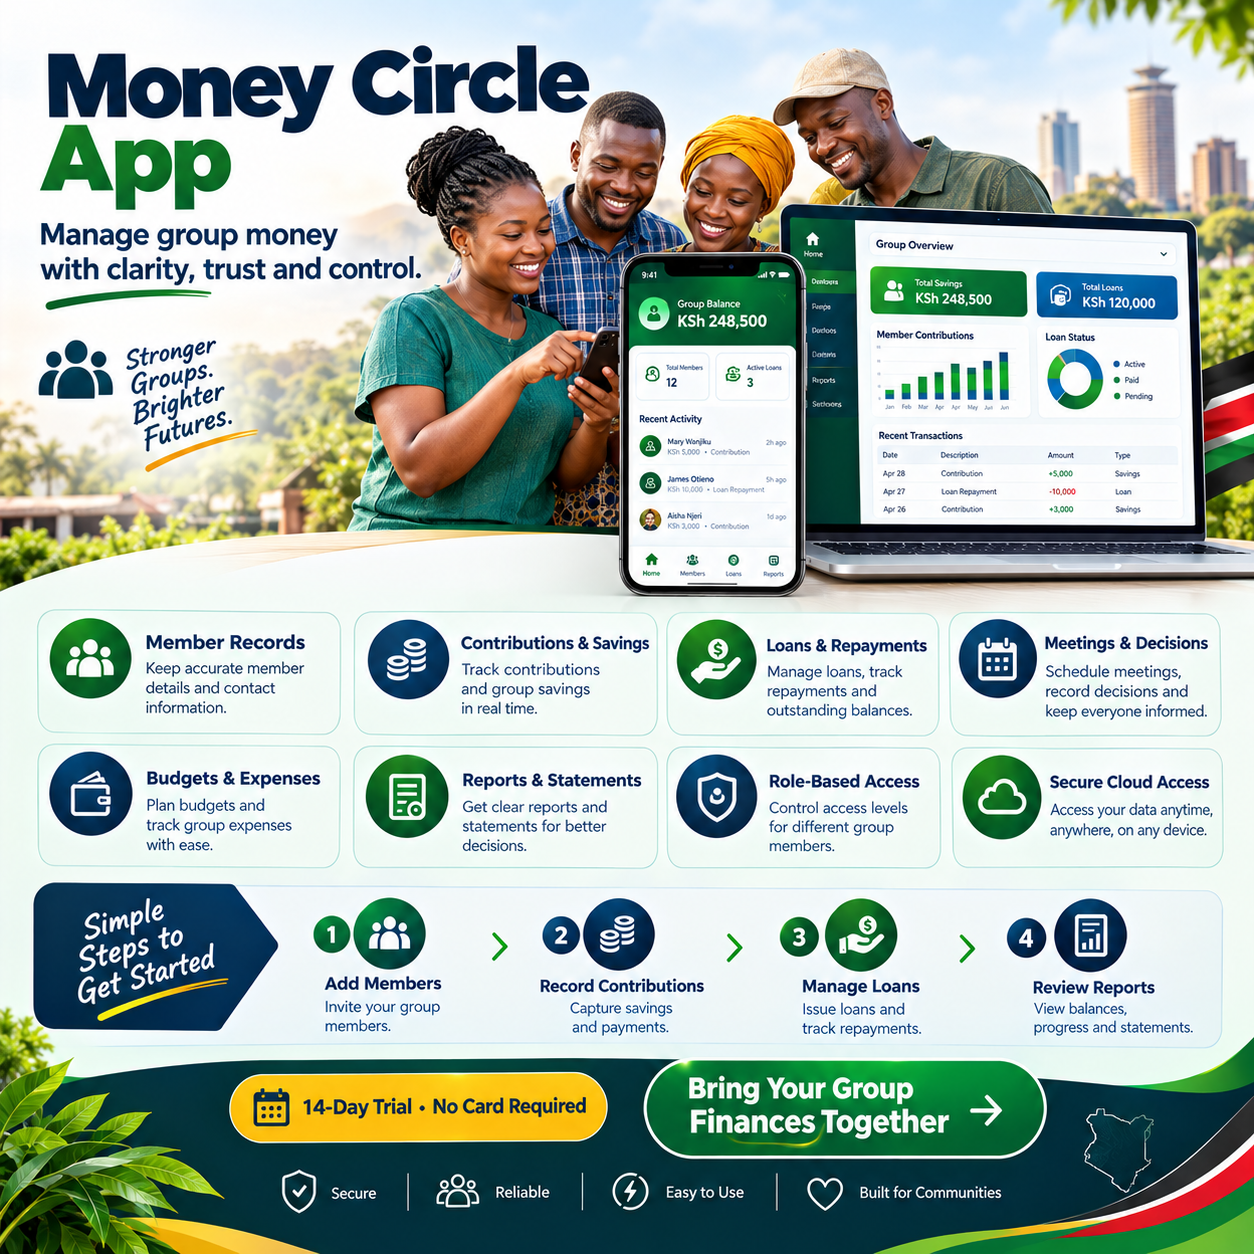
A money circle app is the modern answer to one of humanity’s oldest financial traditions — the practice of neighbors, friends, and colleagues pooling their savings together. In Kenya, this habit runs deep, powering chamas, table banking circles, and welfare societies that move billions of shillings every year. The difference today is that a well-chosen money circle app replaces the notebook, the chase, and the disputes with clean, automatic, verifiable records.
The practice has many names around the world. Kenyans call it chama or table banking, West Africans call it esusu or tontine, and financial researchers call it a rotating savings and credit association. Whatever the name, the mechanics are identical, and so is the modern solution — a purpose-built money circle app that handles the collection, tracking, and reporting automatically.
This guide is the complete journey through that solution. It explains what these apps actually do, why circles fail without them, which features matter, and how to choose and implement the right one. By the end, choosing a money circle app will feel like a decision you can make with total confidence rather than a gamble on unfamiliar technology.
The article is written for treasurers drowning in follow-up messages, chairpersons tired of disputed balances, and founders building new circles that deserve better foundations than chat threads. It is equally written for members who contribute faithfully and simply want to see their money handled with visible order. Everyone in the circle wins when a proper money circle app takes over the administration.
One truth deserves stating before anything else. Money circles do not fail because people are dishonest — they fail because informal records make honesty impossible to prove. That single insight explains both the traditional problems and the modern solution, and it is the thread running through this entire guide to choosing a money circle app.
The timing for this conversation could not be better. Mobile money reaches every pocket in Kenya, smartphones fill every meeting, and purpose-built platforms now cost less per member than a single soda. The conditions that make a money circle app effective have never been more favorable.
There is also genuine good news about the technology itself. These apps have matured from simple payment collectors into complete financial operating systems for groups. Today’s leading money circle app options handle contributions, rotations, loans, fines, welfare, and reporting in one reconciled place.
So read this guide with your circle’s current paperwork beside you. Every section ahead either solves a frustration you will recognize or prevents one you have been lucky to avoid. By the final page, choosing the right money circle app will feel like the most obvious next step your group can take.
What Is a Money Circle?
A money circle is a group of people who agree to contribute money regularly, either lending it to members in turn or investing it toward shared goals. The format is beautifully simple: trust, commitment, and rotation or accumulation form the entire engine. Understanding that simplicity is what makes the value of a money circle app so easy to appreciate.
Two main formats dominate the landscape. Rotating circles — the classic merry-go-round — pay the accumulated pot to one member each cycle until everyone has received their turn. Accumulating circles pool money into a growing fund that gets lent out or invested, and this format is where a money circle app proves most powerful.
Hybrid circles combine both. Members receive their rotation while the group also builds reserves, lends at interest, and invests collectively. Managing that complexity manually is where circles buckle, which is exactly why hybrid groups need a capable money circle app more than anyone.
The circle’s power comes from collective discipline. Individually, two thousand shillings a month buys very little, but twenty people pooling becomes forty thousand monthly — and forty thousand changes lives. That multiplication effect is the economic engine behind every circle, and a money circle app protects that engine from the friction that stalls it.
Kenya’s version of this tradition is among the strongest in the world. Chamas buy land, build rentals, and fund businesses in every county, while table banking circles sustain market traders through countless business cycles. The scale and success of the tradition is precisely why finding the right money circle app matters so much nationally.
Why Money Circles Fail — and How the App Prevents It
The first cause of failure is disputed records. When contributions live in notebooks and memories, two honest people eventually remember the same month differently. Written, centralized, verifiable records are the antidote, and that is precisely the core function of a money circle app.
The second cause is collection fatigue. Treasurers who chase members by hand eventually burn out, and burned-out treasurers resign — often taking the group’s momentum with them. Automated reminders and instant receipts are the relief a money circle app delivers to the official carrying the heaviest load.
The third cause is missed rotations. In rotating circles, the sequence of who receives the pot is the group’s most sensitive record, and confusion there breeds suspicion fast. A money circle app tracks every rotation with dates and confirmations, ending the “who is taking it this month” anxiety permanently.
The fourth cause is silent arrears. A missed contribution is invisible in informal systems until someone goes looking, by which time the debt is old and the conversation is awkward. Arrears dashboards in a money circle app surface problems the moment they form, while they are still easy to fix.
The fifth cause is opaque lending. Circles that lend from their pools without clear records eventually freeze, because nobody trusts the loan book anymore. Loan ledgers, guarantor tracking, and schedules inside a money circle app keep the lending side as clean as the saving side.
The sixth cause is key-person dependency. When all the records live in one treasurer’s notebook and one phone, that person’s departure takes the group’s memory with them. Cloud-based records in a money circle app mean the circle’s history belongs to the group, not to any individual handset.
The deeper pattern behind all six causes is the same. Circles run on trust, and trust needs evidence to survive contact with time. Every feature of a well-chosen money circle app exists to generate that evidence automatically.
The encouraging side of this analysis is equally important. Circles that digitize report fewer disputes, higher collection rates, and longer lifespans within their very first year. The failure patterns are preventable, and the prevention tool is a properly implemented money circle app.
Key Features of a Great Money Circle App
Not every tool deserves the name, so this checklist separates genuine platforms from glorified payment buttons. Test every candidate against these capabilities before your circle commits. Each feature solves a failure mode described above.
Automated contributions come first. The app should invoice every member on schedule, covering monthly payments, share capital, and welfare quotas without anyone pressing a button. Set-and-forget billing is the foundation of a true money circle app.
Rotation tracking comes second for rotating circles. Who received the pot, in which cycle, and what is expected next month should all display on one screen. Rotation clarity is the signature feature that separates a purpose-built money circle app from a generic payment collector.
Real-time M-Pesa reconciliation comes third. Payments must match themselves to the right member, month, and purpose within seconds of landing. Anything less is manual work wearing an app’s clothes, and it disqualifies the platform as a genuine money circle app.
Automatic receipts come fourth. Every payment should trigger instant confirmation to the member, ending the classic “I paid but nobody recorded it” dispute forever. Receipt-on-payment is the trust engine of every leading money circle app.
Member self-service comes fifth. Each person should view their own balance, statement, and payment history anytime, without asking the treasurer. Self-service is what converts a money circle app from an official’s tool into the circle’s shared resource.
Loan and guarantor support comes sixth for lending circles. Applications, approvals, schedules, penalties, and guarantee exposure should all be tracked natively. That depth is what distinguishes a complete money circle app from a simple collector.
Arrears dashboards come seventh. Officials should see every overdue amount aged by days and sorted by member, so problems surface while they are still small. Early warning is the protective layer of a capable money circle app.
Welfare tracking comes eighth. Subscriptions, payouts, and fund balances deserve their own clean ledger within the system, because welfare money is the most sensitive money any circle moves. Dignified administration of that fund is a hallmark of a mature money circle app.
SMS inclusivity comes ninth. Reminders and receipts must reach any phone — smart or not — so no member is excluded by the device they own. Inclusivity is a non-negotiable design principle of every genuine money circle app.
Reporting and exports come tenth. Member statements, collection summaries, and meeting-ready reports should generate in one click, and full data export must be guaranteed. Ownership of your own history is the exit freedom built into a fair money circle app.
Together these ten features form a complete system. Missing any one creates a gap that disputes eventually find, so score candidates honestly against the full list. Completeness is what separates a real money circle app from a partial tool.
Who Benefits Most from a Money Circle App
Large circles feel the relief first. A forty-member group means forty invoices, forty potential reminders, and forty reconciliations every month — work that automation absorbs instantly. Scale is the strongest argument for adopting a money circle app early.
Treasurers with day jobs benefit just as deeply. Volunteer officials cannot spend their lunch breaks chasing colleagues, yet manual systems demand exactly that. Time liberation is the personal dividend of a money circle app running quietly in the background.
Hybrid circles with lending need it most of all. Rotation, reserves, loans, and welfare running simultaneously is simply beyond manual administration. Multi-ledger management is the defining capability of a serious money circle app for complex groups.
Diaspora circles depend on automation almost entirely. Members across time zones need reminders, receipts, and records that work while Nairobi sleeps. Borderless operation is a defining strength of a modern money circle app serving global circles.
New circles gain the cleanest possible start. Records built from the first shilling prevent the archaeology that haunts older groups, and adopting a money circle app on day one costs less than reconstructing three lost years later.
Table banking circles gain structure without losing speed. Rotations, payouts, and the monthly pot are tracked with dates and confirmations that end the old suspicions. That clarity is the quiet upgrade a money circle app brings to the oldest pooling format.
How to Choose the Right Money Circle App
Choose deliberately, because the wrong tool costs more than no tool at all. The tests below turn a crowded market into a short list your circle can trust. Apply them in order with two or three officials present.
Start with your own workflow list. Write down exactly what your circle does monthly — contribution amounts, rotation order, lending rules, welfare quotas — and demand a demonstration of each one. A money circle app evaluated against your real routines reveals itself honestly within one session.
Bring real data to every demo. Ten member names, three months of contributions, and your actual rotation order turn a sales pitch into a rehearsal of your operations. Vendors confident in their money circle app welcome that request instantly.
Test the member experience with your least tech-comfortable member. If they can find their balance and read their statement unaided within a minute, adoption will follow; if they struggle, the app will fail the circle regardless of its features. Usability is the ultimate pass mark for any money circle app.
Probe support quality directly. Ask who answers on collection day, in which language, and within what hours, because money problems never wait for business hours. Responsive Kenyan support is the relationship test that separates a genuine money circle app partner from an anonymous platform.
Insist on the total first-year cost in writing. Subscription, SMS volumes, onboarding, and any member limits should appear on one quoted figure. Transparent pricing is the honesty marker of a trustworthy money circle app, and hesitation to provide it is itself an answer.
Confirm data ownership and export before signing anything. Your circle’s history belongs to the circle, and full download must be guaranteed at any time, in usable formats. Exit freedom is the long-term protection built into a fair money circle app.
Finally, check references from circles of your own size and type. Current users reveal what demos never can — how the platform behaves in month twelve, not just in the demo room. Reference calls are the final validation step before adopting any money circle app.
Implementing the App: A Smooth Four-Week Plan
Adoption succeeds when it is planned as a journey rather than imposed as a decree. The four-week sequence below has carried hundreds of Kenyan circles from notebooks to automation without a single argument. Each week builds confidence for the next.
Week one is for clean data. Reconcile every outstanding balance, rotation position, and fine before anything moves into the new system, because dirty beginnings become permanent disputes. Accurate history is the prerequisite for a successful money circle app launch.
Week two is for faithful configuration. Load members, set contribution schedules, and enter the rotation order exactly as the circle agreed it, with two officials verifying together. Careful setup is what makes the money circle app enforce the circle’s actual rules rather than the vendor’s defaults.
Week three is the collective launch. Hold a live demonstration at a meeting, showing every member how to pay, check their rotation position, and read their statement. Circles that train together adopt a money circle app almost without resistance, and no member feels left behind.
Week four is the parallel run. Keep the old method and the new system side by side for one full cycle, then compare month-end totals openly. When the figures match, the circle graduates permanently to its money circle app — and the old notebook is retired with a small, satisfying ceremony.
What It Costs and What It Returns
Pricing follows familiar patterns across the market. Most platforms charge between one and three thousand shillings monthly for typical circles, with SMS volumes as the main add-on and annual prepayment discounts commonly available. Always request the total first-year figure when comparing any money circle app.
Now weigh the returns honestly. Recovered arrears, prevented disputes, reclaimed treasurer hours, and avoided losses routinely exceed the subscription many times over. Most circles find that a money circle app pays for itself within the very first quarter of cleaner collections.
Do the arithmetic with your own figures before the circle votes. Take last year’s uncollected contributions and unreconciled discrepancies, place them beside one year of subscription, and show both numbers on a single page. That page is usually the most persuasive slide in the entire case for a money circle app.
Remember the unpriced returns too. Officials who sleep well, members who feel equally treated, and meetings that discuss plans instead of payments are worth more than any fee by an honest measure. Peace of mind is the invisible dividend of a well-chosen money circle app.
Common Mistakes to Avoid
The first classic mistake is switching without reconciling history. Uncleaned balances imported into a new system become permanent disputes that no feature can undo. Clean data is the non-negotiable prerequisite for any money circle app migration.
The second mistake is ignoring the circle’s agreements during configuration. The app must enforce your rotation order, fines, and schedules exactly as the members decided them, not the vendor’s defaults. Faithful setup is the discipline behind a money circle app that strengthens rather than replaces your rules.
The third mistake is hiding the switch from members. Surprise system changes breed resistance that a simple, warm explanation would have prevented entirely. Transparent launches are the adoption secret behind every successful money circle app deployment.
The fourth mistake is abandoning human warmth because the app sends reminders. Officials should still personally reach out when a member’s pattern shows genuine struggle, because systems enforce rules while humans offer help. The healthiest circles pair their money circle app with genuine care.
Real Stories from Kenyan Circles
The Nakuru merry-go-round spent its first years arguing about late contributions, with two members nearly leaving over disputed balances. After adopting automation, arrears fell to nearly zero within three cycles, and the treasurer described the platform as “a colleague who never sleeps.” Their transformation is the standard testimony for a money circle app done right.
The Kitengela landlords’ circle collects contributions from members in five countries. Reminders arrive on time everywhere, receipts confirm instantly, and the AGM statements generate themselves in minutes. Their diaspora members call the money circle app the reason distance stopped mattering.
The Eldoret boda fleet runs on weekly contributions from members with irregular incomes. Partial payments tracked automatically ended the shame of falling behind mid-week, and discipline improved without a single confrontation. Fairness, they say, is the unexpected gift of their money circle app.
A fourth circle pairs the same discipline across everything it owns. Contributions flow automatically through the group’s platform while tenants and rent flow through Tas.co.ke on the property side. Two automated streams and one peaceful committee — the complete picture of a money circle app working alongside specialized tools.
Frequently Asked Questions
Do members need smartphones to participate? No — reminders and receipts reach any phone through SMS, while smartphone users enjoy richer dashboards and statements. Inclusivity is a design principle of every serious money circle app, so nobody is excluded by the device they own.
Does the app hold our money? No — payments go directly into the circle’s own paybill, till, or bank account, and the app only records, reconciles, and reports. Your funds never sit with the vendor, which is the foundational safety design of a trustworthy money circle app.
What happens if a member pays the wrong amount? The system records the actual payment, updates the balance, and flags the difference for gentle follow-up. Graceful handling of imperfect payments is standard behavior in a well-built money circle app.
Can it handle rotating payouts and loans at the same time? Yes — rotation schedules and loan ledgers run side by side within one system, each with its own rules and reports. That dual capability is what distinguishes a mature money circle app from a simple collector.
How quickly will we see results? Most circles report faster collections and fewer disputes within the very first billing cycle. The treasurer usually notices first, in reclaimed evenings and a quieter phone — the immediate reward of a money circle app working properly.
What does it cost for a typical circle? Budget between one and three thousand shillings monthly on a standard plan, plus modest SMS charges. At that level, a money circle app costs each member less than a soda per year while protecting thousands in pooled savings.
We also own rental units — can the same app collect rent? Property collections deserve a dedicated system, and the smartest circles run both side by side. Contributions flow through your money circle app while tenants, rent invoicing, and owner statements run on Tas.co.ke — one connected ecosystem for everything the circle collects.