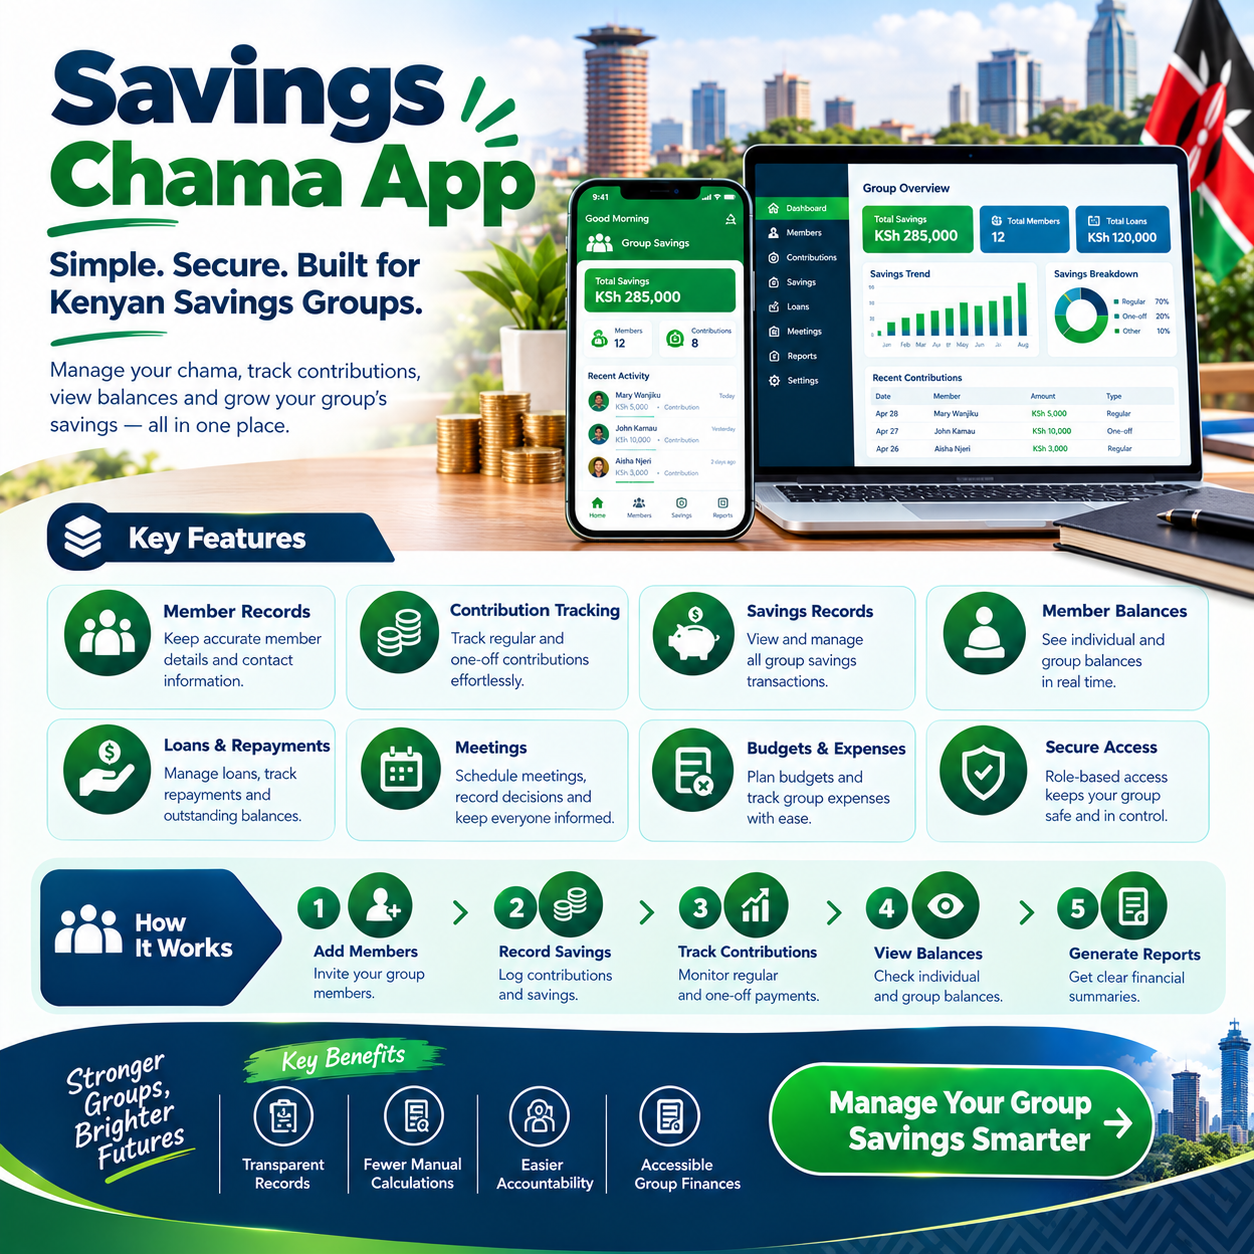
A savings chama app is the modern engine behind Kenya’s most successful investment groups, converting monthly contributions into tracked, growing, verifiable wealth. Savings chamas form the backbone of the country’s informal financial sector — buying plots, building rentals, and funding dreams that no single member could afford alone. The difference between groups that thrive and groups that stall is rarely ambition; it is whether a proper savings chama app sits at the center of their money.
The savings chama itself is a beautiful, proven model. Members contribute faithfully, the pool grows month after month, and the group decides together where that growing capital should go. What the traditional model lacks is infrastructure — records that reconcile, balances that update themselves, and statements that members can verify anytime. That infrastructure gap is precisely what a purpose-built savings chama app was created to close.
This guide is the complete journey through that solution. It explains what these apps actually do, why savings groups struggle without them, which features matter most, and how to choose, implement, and afford the right one. By the final page, selecting a savings chama app will feel like a decision you can make with total confidence rather than a gamble on unfamiliar technology.
The article is written for treasurers carrying the weight of every figure, chairpersons who must present the group’s position at every AGM, and members who contribute faithfully and deserve to see their sacrifice building something visible. It is equally written for founders launching new chamas that deserve clean foundations from the first shilling. Everyone in the group wins when the right savings chama app becomes its shared financial backbone.
One truth deserves stating before anything else. Savings groups do not fail because their members stop caring — they fail because informal records let contributions blur, balances drift, and trust quietly erode. Every capability inside a well-chosen savings chama app exists to stop that erosion before it starts.
There is a second truth that follows close behind. Savings is a long game, and the records must survive the whole journey. A group saving toward land in year one needs its year-five balances to be just as provable as its first deposit. That permanence is the defining promise of a cloud-based savings chama app, where history never fades with any notebook or handset.
The timing for this conversation has never been better. Mobile money reaches every pocket, smartphones fill every meeting, and purpose-built platforms now cost less per member than a single soda each month. The conditions that make a savings chama app transformative have never been more accessible than they are right now.
There is also a deeper reward hiding behind the record-keeping convenience. Groups that digitize their savings report faster accumulation, calmer meetings, and bolder investments — because members who can see their money growing contribute with more confidence. That compounding confidence is the real story inside every savings chama app success.
So read this guide with your group’s current savings records open beside you. Note what your group tracks well today and which gaps the coming sections will close. By the end, you will know exactly what the right savings chama app should deliver — and how to get it without stress.
What Is a Savings Chama App?
A savings chama app is a digital platform that manages the complete savings life of an investment group — from invoicing members to reconciling payments to displaying every balance in real time. It replaces the notebook, the spreadsheet, and the chat-thread receipt hunt with one structured, searchable system. That centralization is what distinguishes a genuine savings chama app from a simple payment collector.
Think of it as the group’s permanent financial memory. It never forgets a payment, never loses a receipt, and never confuses one member’s contribution with another’s. That reliability is the foundational value of every serious savings chama app on the market.
The finest platforms are built specifically for Kenyan savings culture. They understand monthly contributions, share capital, table banking rotations, welfare subscriptions, and the reports officials must present at the AGM. That local fluency is what separates a purpose-built savings chama app from generic international tools awkwardly translated for the market.
Most modern options are cloud-based, meaning records live securely online rather than on one person’s phone. Officials access them from anywhere, and the group’s history survives phone theft, resignation, and the passage of years. That resilience is a defining feature of every mature savings chama app in the market today.
It is worth separating these platforms from the payment channels they sit behind. A paybill or till receives money, but it cannot invoice, remind, match, or report — the group still does all of that by hand. Only a complete savings chama app covers the entire journey from reminder to reconciliation to statement.
The best apps also serve three audiences at once. Officials use them to run the group, members use them to verify their own standing, and successors use them to inherit clean records. That triple service is the design standard behind every leading savings chama app today.
Finally, understand what the app is not. It is not a bank, not a wallet, and not a place where group money rests — payments flow directly into the group’s own accounts, and the app records and reconciles them. That separation of money from records is the safety architecture behind every trustworthy savings chama app.
Why Savings Chamas Struggle Without One
The first struggle is disputed balances. When contributions live in notebooks and memories, two honest members eventually remember the same month differently, and no referee exists. Verified, centralized records from a savings chama app end those disputes before they form.
The second struggle is silent arrears. A missed contribution is invisible in informal systems until someone goes looking, by which time the debt is old and the conversation is awkward. Arrears dashboards in a savings chama app surface problems the moment they form, while a gentle reminder still fixes them.
The third struggle is collection fatigue. Treasurers who chase members by hand spend their evenings messaging, matching, and defending figures — unpaid labor that eventually breaks even the most devoted volunteer. Automation inside a savings chama app returns those evenings to the official and the official’s family.
The fourth struggle is blending confusion. Savings, share capital, and welfare money all flow into groups, and mixing them in one ledger distorts every figure the group depends on. Separate, clean ledgers are the structural discipline a proper savings chama app enforces from day one.
The fifth struggle is key-person dependency. When all the records live in one treasurer’s notebook and one phone, that person’s departure takes the group’s memory with them. Cloud-based history in a savings chama app means the group’s story belongs to the group, not to any individual handset.
The sixth struggle is growth friction. Groups that begin with ten members find their manual systems cracking at twenty and collapsing at forty, just when the savings pool is getting serious. Scalable administration is exactly what a mature savings chama app provides as the membership and the money both grow.
The seventh struggle is reporting embarrassment. Every AGM exposes the gap between what members expect to see and what the treasurer can actually produce on paper. One-click statements and annual summaries from a savings chama app convert that moment from interrogation into celebration.
The eighth struggle is opportunity cost. Groups that cannot state their exact balance instantly miss deals that reward fast, confident money. Real-time figures from a savings chama app turn “let me check and get back to you” into an answer given on the spot.
The pattern across all eight struggles is identical. Informal systems depend on memory, moods, and goodwill, while formal systems depend on structure that never tires. Groups that adopt a proper savings chama app simply stop fighting battles that software has already won.
Key Features of a Great Savings Chama App
Not every tool deserves the name, so this checklist separates genuine platforms from glorified payment buttons. Test every candidate against these capabilities before your group commits. Each feature solves a failure mode described above.
Automated contribution invoicing comes first. The app should generate invoices on schedule — monthly savings, share capital top-ups, welfare quotas — without anyone pressing a button. Set-and-forget billing is the foundation of a true savings chama app.
Real-time M-Pesa reconciliation comes second. Payments must match themselves to the right member, month, and purpose within seconds of landing through the group’s paybill or till. Anything less is manual work wearing an app’s clothes, and it disqualifies the platform as a genuine savings chama app.
Automatic receipts come third. Every payment should trigger instant confirmation to the member, ending the classic “I paid but nobody recorded it” dispute forever. Receipt-on-payment is the trust engine of every leading savings chama app.
Member self-service comes fourth. Each person should view their own balance, statement, and payment history anytime, without asking the treasurer for anything. Self-service is what converts a savings chama app from an official’s tool into the group’s shared resource.
Separate ledgers for each fund come fifth. Monthly savings, share capital, welfare, and project funds should live apart within one system, because blended money is where confusion breeds. Ledger discipline is a hallmark of a mature savings chama app.
Growth tracking comes sixth. The app should display the savings pool rising month over month and year over year, so progress becomes visible motivation. Compounding made visible is the motivational core of a good savings chama app.
Arrears dashboards come seventh. Officials should see every overdue amount aged by days and sorted by member, so problems surface while they are still small. Early warning is the protective layer of a capable savings chama app.
Fine automation comes eighth. Late payments should trigger fines exactly as the constitution prescribes, applied impartially to everyone including officials. That impartial enforcement is the discipline layer of a serious savings chama app.
SMS inclusivity comes ninth. Reminders and receipts must reach any phone — smart or not — so no member is excluded by the device they own. Inclusivity is a non-negotiable design principle of every genuine savings chama app.
Offline resilience comes tenth. Collections happen in markets, villages, and basements where networks fail, and records entered offline must sync safely later. Resilience without connectivity is the reliability mark of a serious savings chama app.
Reporting and exports come eleventh. Member statements, collection summaries, and AGM-ready reports should generate in one click, and full data export must be guaranteed. Ownership of your own history is the exit freedom built into a fair savings chama app.
Security and roles complete the checklist. Only authorized officials should configure rules or approve changes, and every action should be logged permanently with a name and timestamp. Controlled power is the governance layer that separates a professional savings chama app from a casual tool.
Together these twelve features form a complete system. Missing any one creates a gap that disputes eventually find, so score candidates honestly against the full list. Completeness is what separates a real savings chama app from a partial one.
When comparing platforms, print this checklist and score each candidate against it with two or three officials present. Identical scorecards are the only honest way to compare products that present very differently in demonstrations. Structured evaluation turns a crowded market into a confident choice.
The Savings Journey: How the App Serves Every Stage
A savings chama passes through recognizable stages, and a good app serves each one differently. Understanding the journey helps groups see why the tool grows more valuable over time rather than less. That expanding value is the strategic case for adopting a savings chama app early.
The formation stage comes first. A new group needs clean registration, clear contribution schedules, and records built from the very first shilling. Starting digital is the cheapest possible moment for a group to adopt a savings chama app, because there is no messy history to migrate.
The accumulation stage follows. Contributions flow monthly, the pool compounds, and balances grow into figures worth protecting seriously. This is the stage where the automated reconciliation of a savings chama app proves its worth every single month.
The first-investment stage arrives next. The group makes its first land purchase or deposit, and every shilling of that decision must trace to recorded contributions. Documented capital is what gives a group its negotiating confidence, backed by the clean history its savings chama app has maintained.
The growth stage brings multiple funds. Savings, welfare, and project money run in parallel, each with its own targets and its own ledger. Multi-fund management is the stage where the structural depth of a serious savings chama app becomes indispensable.
The maturity stage completes the journey. Years of verified records now serve dividend calculations, loan applications, and succession planning with equal ease. That institutional archive is the long-game reward of a group that chose its savings chama app wisely at the beginning.
Who Benefits Most from a Savings Chama App
Large groups feel the relief first. A forty-member chama means forty invoices, forty potential reminders, and forty reconciliations every month — work that automation absorbs instantly. Scale is the strongest argument for adopting a savings chama app early.
Long-horizon groups need it just as much. Circles saving toward buildings and land require records that stay trustworthy across five, ten, and fifteen years. That permanence is the defining strength of a cloud-based savings chama app.
Diaspora groups depend on automation almost entirely. Members across time zones need reminders, receipts, and balances that work while Nairobi sleeps. Borderless operation is a natural capability of a modern savings chama app serving global circles.
Welfare-heavy groups gain special value. Societies built around emergency response need instant access to subscription standing and fund balances when tragedy arrives. Prepared compassion is the humane dividend of a savings chama app with strong welfare ledgers.
Table banking circles gain structure without losing speed. Rotations, payouts, and the monthly pot are tracked with dates and confirmations that end the old suspicions. That clarity is the quiet upgrade a savings chama app brings to the oldest pooling format.
New groups gain the cleanest possible start. Records built from the first shilling prevent the archaeology that haunts older groups, and a savings chama app adopted on day one costs far less than reconstructing three lost years later.
Property-owning groups run two financial streams, and each deserves its right tool. Savings and group projects form one stream while tenants and rent form another. The strongest setups pair the group’s savings chama app with a dedicated property system so nothing slips between the two.
How to Choose the Right Savings Chama App
Choose deliberately, because the wrong tool costs more than no tool at all. The tests below turn a crowded market into a short list your group can trust. Apply them in order with two or three officials present.
Start with your own workflow list. Write down exactly what your group does monthly — contribution amounts, fund types, fine rules, reporting needs — and demand a demonstration of each one. A savings chama app evaluated against your real routines reveals itself honestly within one session.
Bring real data to every demo. Ten member names, three months of contributions, and your actual fund structure turn a sales pitch into a rehearsal of your operations. Vendors confident in their savings chama app welcome that request instantly.
Test the reconciliation live. Ask the vendor to show one M-Pesa payment landing and matching automatically to the right member, with no manual step anywhere. That single demonstration is the decisive moment for groups evaluating any savings chama app.
Test the member experience with your least tech-comfortable official. If they can find their balance and read their statement unaided within a minute, adoption will follow; if they struggle, the app will fail the group regardless of its features. Usability is the ultimate pass mark for any savings chama app.
Probe support quality directly. Ask who answers when a payment fails to reflect on collection day, in which language, and within what hours. Responsive Kenyan support is the relationship test that separates a genuine savings chama app partner from an anonymous platform.
Insist on the total first-year cost in writing. Subscription, SMS volumes, onboarding, and any member limits should appear on one quoted figure. Transparent pricing is the honesty marker of a trustworthy savings chama app, and hesitation to provide it is itself an answer.
Confirm data ownership and export before signing anything. Your group’s history belongs to the group, and full download must be guaranteed at any time, in usable formats. Exit freedom is the long-term protection built into a fair savings chama app.
Finally, check references from groups of your own size and type. Current users reveal what demos never can — how the platform behaves in month twelve, not just in the demo room. Reference calls are the final validation step before adopting any savings chama app.
Implementing the App: A Smooth Four-Week Plan
Adoption succeeds when it is planned as a journey rather than imposed as a decree. The four-week sequence below has carried hundreds of Kenyan groups from notebooks to automation without a single argument. Each week builds confidence for the next.
Week one is for clean data. Reconcile every outstanding balance and fine before anything moves into the new system, because dirty beginnings become permanent disputes. Accurate history is the prerequisite for a successful savings chama app launch.
Week two is for faithful configuration. Load members, set contribution schedules, and mirror the constitution’s rules line by line, with two officials verifying together. Careful setup is what makes the savings chama app enforce the group’s actual rules rather than the vendor’s defaults.
Week three is the collective launch. Hold a live demonstration at a meeting, showing every member how to pay, check their balance, and read their statement. Groups that train together adopt a savings chama app almost without resistance, and no member feels left behind.
Week four is the parallel run. Keep the old method and the new system side by side for one full billing cycle, then compare month-end totals openly. When the figures match, the group graduates permanently to its savings chama app — and the old notebook is retired with a small, satisfying ceremony.
After graduation, review the first ninety days openly at a meeting. Collection rates, recording accuracy, and member feedback all confirm the value gained. That first review is the moment the savings chama app stops being a project and becomes permanent infrastructure.
What It Costs and What It Returns
Pricing follows familiar patterns across the market. Most platforms charge between one and three thousand shillings monthly for typical groups, with SMS volumes as the main add-on and annual prepayment discounts commonly available. Always request the total first-year figure when comparing any savings chama app.
Now weigh the returns honestly. Recovered arrears, prevented disputes, reclaimed treasurer hours, and better investment decisions routinely exceed the subscription many times over. Most groups find that a savings chama app pays for itself within the very first quarter of cleaner collections.
Do the arithmetic with your own figures before the group votes. Take last year’s uncollected contributions and unreconciled discrepancies, place them beside one year of subscription, and show both numbers on a single page. That page is usually the most persuasive slide in the entire case for a savings chama app.
Remember the unpriced returns too. Officials who sleep well, members who feel equally treated, and meetings that discuss plans instead of payments are worth more than any fee by an honest measure. Peace of mind is the invisible dividend of a well-chosen savings chama app.
Common Mistakes to Avoid
The first classic mistake is switching without reconciling history. Uncleaned balances imported into a new system become permanent disputes that no feature can undo. Clean data is the non-negotiable prerequisite for any savings chama app migration.
The second mistake is ignoring the constitution during configuration. The app must enforce your fines, schedules, and fund rules exactly as the members voted them, not the vendor’s defaults. Faithful setup is the discipline behind a savings chama app that strengthens rather than replaces your rules.
The third mistake is hiding the switch from members. Surprise system changes breed resistance that a simple, warm explanation would have prevented entirely. Transparent launches are the adoption secret behind every successful savings chama app deployment.
The fourth mistake is abandoning human warmth because the app sends reminders. Officials should still personally reach out when a member’s pattern shows genuine struggle, because systems enforce rules while humans offer help. The healthiest groups pair their savings chama app with genuine care.
The fifth mistake is choosing by price alone. The cheapest tool that lacks reconciliation, reporting, or support creates hidden costs in workarounds and lost hours. Value, not price, is the correct lens for judging any savings chama app.
Real Stories from Kenyan Groups
The Nakuru welfare table spent its first year reminding twelve members one by one, with arrears stubbornly hovering around a third of collections. After adopting automation, their collection rate climbed above ninety-five percent within two cycles, and the treasurer described the platform as “a colleague who never sleeps.” Their transformation is the standard testimony for a savings chama app done right.
The Kitengela landlords’ chama collects contributions from members in five countries. Reminders arrive on time everywhere, receipts confirm instantly, and the AGM statements generate themselves in minutes. Their diaspora members call the savings chama app the reason distance stopped mattering.
The Eldoret youth group tells the growth story. Their three-year savings history, documented in clean statements, convinced a hesitant bank to finance their first building. Institutional credibility, they discovered, is the compounding reward of disciplined records.
A fourth group pairs the same discipline across everything it owns. Savings flow automatically through the group’s platform while tenants and rent flow through Tas.co.ke on the property side. Two automated streams and one peaceful committee — the complete picture of a savings chama app working alongside specialized tools.
Frequently Asked Questions
Do members need smartphones to participate? No — reminders and receipts reach any phone through SMS, while smartphone users enjoy richer dashboards and statements. Inclusivity is a design principle of every serious savings chama app, so nobody is excluded by the device they own.
Does the app hold our money? No — payments go directly into the group’s own paybill, till, or bank account, and the app only records, reconciles, and reports. Your funds never sit with the vendor, which is the foundational safety design of a trustworthy savings chama app.
What happens if a member pays the wrong amount? The system records the actual payment, updates the balance, and flags the difference for gentle follow-up. Graceful handling of imperfect payments is standard behavior in a well-built savings chama app.
Can it handle savings, welfare, and share capital at the same time? Yes — multiple ledgers run side by side within one system, each with its own rules and reports. That completeness is what distinguishes a mature savings chama app from a simple collector.
How quickly will we see results? Most groups report faster collections and fewer disputes within the very first billing cycle. The treasurer usually notices first, in reclaimed evenings and a quieter phone — the immediate reward of a savings chama app working properly.
What does it cost for a typical group? Budget between one and three thousand shillings monthly on a standard plan, plus modest SMS charges. At that level, a savings chama app costs each member less than a soda per year while protecting thousands in pooled savings.
How long does implementation take? Four weeks is the proven rhythm — one week reconciling data, one configuring, one launching collectively, and one running parallel. Groups that follow the sequence adopt their savings chama app without a single argument.
Is our group’s data safe on the platform? Reputable providers encrypt data, maintain backups, and restrict access through role-based permissions, making digital records far safer than any single notebook or phone. Choosing an established provider with a proven track record is the best security decision a group can make for its savings chama app.
We also own rental units — can the same app collect rent? Property collections deserve a dedicated system, and the smartest groups run both side by side. Savings flow through your savings chama app while tenants, rent invoicing, and owner statements run on Tas.co.ke — one connected ecosystem for everything the group collects.