Group Savings Management Software Kitengela: A Complete Guide for Chamas
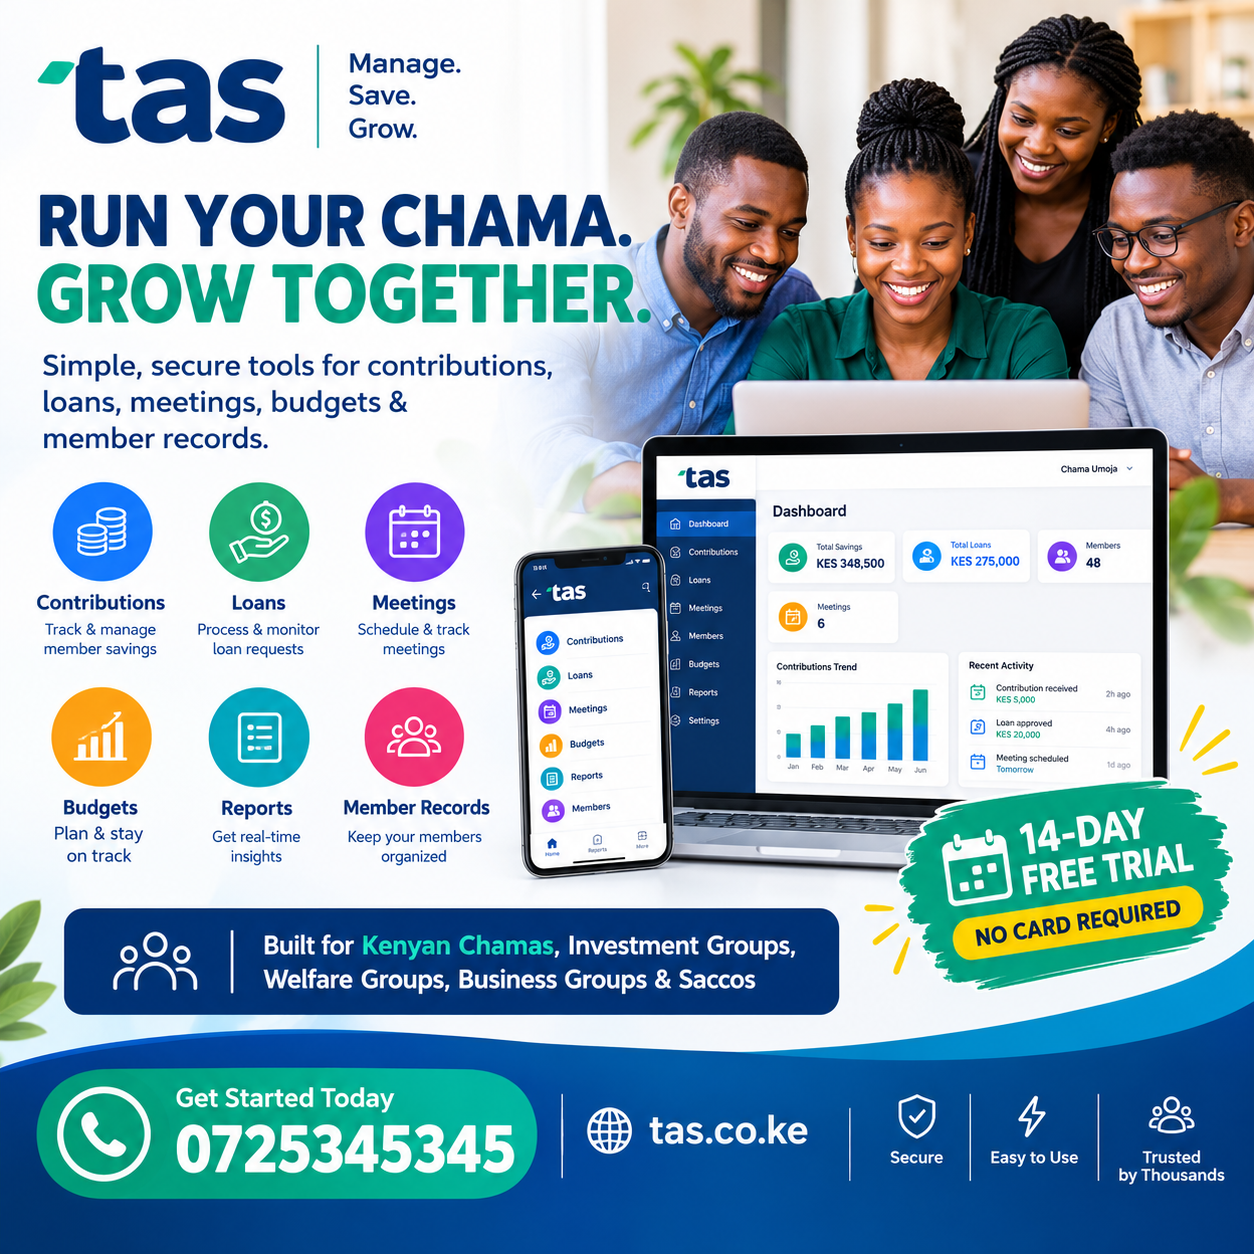
Group Savings Management Software Kitengela: A Complete Guide for Chamas and Investment Groups
Managing a savings group requires more than collecting money and recording payments in a notebook. Members need accurate contribution records, transparent financial reports, clear loan balances, and reliable information about how their pooled funds are being used. Group Savings Management Software Kitengela offers a relevant search starting point for groups looking to explore digital tools for organising their savings activities, improving accountability, and simplifying day-to-day administration.
Kitengela has a diverse community of households, entrepreneurs, employees, traders, professionals, and investors who may participate in chamas, table-banking groups, welfare associations, and investment clubs. Although these groups may have different objectives, they often face similar administrative challenges: following up on contributions, maintaining accurate records, calculating interest, monitoring outstanding loans, and preparing reports that members can understand.
When records are scattered across exercise books, spreadsheets, messaging applications, and individual mobile money statements, even a well-organised group can struggle to maintain a complete financial picture. A digital management system can bring these activities together, giving authorised officials a more structured way to manage information and helping members understand their financial commitments.
This guide explains how savings groups in Kitengela can approach digital management, which features to prioritise, how to improve financial transparency, and what to consider before adopting software for their group.
1. Understanding Savings Group Management in Kitengela
Savings groups are built around a common purpose. Members agree to contribute money, follow established rules, and use the pooled funds according to their group’s constitution or operating agreement. Some groups save for emergencies, while others invest in land, businesses, education, housing, or other long-term objectives.
The challenge is that every contribution and transaction creates a recordkeeping responsibility. Someone must confirm who paid, how much was received, whether the payment was allocated correctly, and what balance remains.
A group exploring Group Savings Management Software Kitengela should begin by identifying these responsibilities rather than choosing a system based solely on its appearance or price.
Common types of savings groups
Different groups have different administrative needs.
- Chamas: Members contribute regularly towards a shared savings or investment objective.
- Table-banking groups: Members contribute money that may be borrowed by participants under agreed conditions.
- Investment clubs: Members pool funds for projects, assets, or other investments.
- Welfare groups: Members contribute towards emergencies, bereavements, medical expenses, and other shared needs.
- Employee savings groups: Colleagues organise regular contributions and may provide loans to eligible members.
- Community savings associations: Participants organise savings activities around a neighbourhood, profession, or common interest.
A system suitable for a small welfare group may not be sufficient for a large investment club with multiple projects, complex loan calculations, and formal reporting requirements.
Why Kitengela groups need organised records
As groups grow, the number of transactions usually increases. More members mean more contribution entries, questions about balances, loan applications, repayments, and financial decisions.
For example, a group with 25 members who each contribute KSh 2,000 monthly expects KSh 50,000 in contributions per month, assuming every member pays the full amount. Over twelve months, that represents KSh 600,000 in scheduled contributions before considering expenses, loans, investment returns, penalties, or other transactions.
Without consistent records, officials may find it difficult to explain differences between expected and actual collections. A digital system can help organise these records and identify transactions requiring attention.
2. What Is Group Savings Management Software?
Group savings management software is a digital application designed to help groups record, monitor, and administer their financial activities. Depending on the product, it may support member registration, contribution tracking, loan administration, payment reconciliation, financial reporting, meeting records, and reminders.
Rather than maintaining several disconnected records, a group can use a central system to organise its activities. The precise features vary by provider, so groups should verify the functions available in any particular package.
For a group researching Group Savings Management Software Kitengela, the main objective should be to find a tool that matches its operating rules and makes routine financial work easier.
How a digital system works
A typical implementation follows several stages:
- The group registers its members and records their relevant details.
- Officials configure contribution schedules, membership rules, and other approved policies.
- Contributions and other financial transactions are entered or imported through supported methods.
- Loan applications, approvals, disbursements, and repayments are recorded.
- The system calculates balances according to its configured rules.
- Officials review reports and reconcile them against actual financial records.
- Members receive information through the communication methods supported by the system.
Automation can reduce repetitive work, but it does not remove the need for human oversight. Officials must still verify transactions, correct errors, approve decisions, and protect confidential information.
Software versus manual recordkeeping
| Activity | Manual approach | Digital approach |
|---|---|---|
| Member records | Exercise books or separate files | Centralised member database |
| Contribution tracking | Individual entries and calculations | Structured transaction records |
| Loan balances | Manual calculations | Configured calculations and repayment tracking |
| Financial reporting | Compiled from several records | Reports generated from recorded data |
| Payment reconciliation | Comparing receipts and statements manually | Supported matching and reconciliation tools |
| Member communication | Individual calls and messages | Available reminders and communication features |
| Historical records | Paper files or scattered spreadsheets | Searchable digital records and supported exports |
Digital records are most useful when the group establishes consistent procedures for entering, reviewing, and correcting information.
3. Benefits of Digitising Group Savings Activities
The greatest benefit of a digital management system is not simply replacing paper. It is improving the reliability and accessibility of the information used to run the group.
Better contribution tracking
Contributions are the foundation of many savings groups. Each payment needs to be allocated to the correct member, contribution period, and financial category.
A group considering Group Savings Management Software Kitengela should look for a system that can show scheduled contributions, payments received, outstanding amounts, and historical transactions.
This can help officials answer practical questions:
- Which members have paid for the current month?
- Which contributions remain outstanding?
- Did a member pay in instalments?
- Was a payment allocated to the correct period?
- What is the total amount collected so far?
A clear contribution history can also reduce disagreements when members review their individual statements.
Greater financial transparency
Transparency means that financial decisions and records can be explained and checked. It does not mean that every member should have unrestricted access to every personal detail.
A well-designed system can provide authorised officials with financial summaries and allow members to view relevant information about their own contributions, loans, and balances.
For groups investigating Group Savings Management Software Kitengela, access permissions should be an important consideration. The system should support appropriate distinctions between ordinary members, treasurers, secretaries, committee members, and administrators.
More efficient administration
Treasurers often spend considerable time recording payments, calculating balances, preparing statements, and responding to member questions. A digital workflow can reduce repeated calculations and make routine reporting faster.
Time saved on administration can be redirected towards reviewing investment opportunities, improving member participation, and planning future activities.
More reliable financial planning
Accurate records help groups distinguish between money available for lending, funds reserved for emergencies, amounts committed to investments, and outstanding loans.
This distinction is important because a group may appear to have substantial total assets while much of its money is tied up in loans or investments that cannot be converted into cash immediately.
Easier preparation for meetings
When members meet to discuss their finances, they need understandable information rather than disconnected figures.
A group using Group Savings Management Software Kitengela as a research reference should assess whether its preferred system can produce useful summaries for meetings, including contributions received, expenses, loan balances, and unresolved reconciliation items.
Reports should be prepared from verified transactions, with adjustments documented rather than hidden.
4. Essential Features to Look For
Not every group needs a complicated application. The right choice depends on its membership, financial activities, operating rules, and budget.
Member registration and profiles
The software should make it possible to maintain a reliable register of members. Depending on the group’s needs, records may include member numbers, contact information, joining dates, membership status, and relevant account details.
A member profile should help officials identify the correct person without unnecessarily exposing confidential information.
For groups exploring Group Savings Management Software Kitengela, it is worth checking whether the system can maintain a history of membership changes and prevent duplicate records.
Contribution schedules
Groups may collect money weekly, monthly, quarterly, or according to a project-specific schedule.
A useful system should accommodate the group’s actual rules instead of forcing every group into one fixed contribution pattern.
It should ideally support:
- Regular contribution schedules.
- Different approved contribution amounts.
- Recording partial payments.
- Identification of outstanding contributions.
- Historical payment statements.
- Clear treatment of late payments and penalties.
Loan management
Some savings groups lend money to members. Their software should support the group’s approved lending policies and maintain a complete history of each loan.
Relevant capabilities may include loan applications, approval records, principal amounts, interest settings, repayment schedules, penalties where applicable, outstanding balances, and completed-loan histories.
When evaluating Group Savings Management Software Kitengela, confirm how the system calculates interest. Flat-rate and reducing-balance methods can produce different results, so the method must match the group’s documented policy.
Financial reporting
Useful reports may include contribution summaries, cash receipts, expenses, loan disbursements, repayment histories, arrears, and balances by financial category.
Reports should clearly identify the reporting period and distinguish actual transactions from forecasts or outstanding commitments.
Member statements
Members benefit from being able to review their own transactions. Statements can reduce repetitive questions and give members an opportunity to identify mistakes early.
Before selecting Group Savings Management Software Kitengela, check whether members can access statements independently or whether officials must generate and distribute them.
Record exports and backups
A group should be able to preserve its financial history. Ask whether records can be exported into practical formats and how backups are created, retained, and restored.
Data portability is especially important when a group changes software providers or needs to retain historical records after an official leaves office.
5. Managing Contributions Accurately
Contribution tracking deserves special attention because small errors can accumulate over time.
Suppose a group has 40 members, each expected to contribute KSh 1,500 per month. Its scheduled monthly collection is KSh 60,000. If the group records only KSh 57,000, officials should investigate the difference instead of automatically assuming that members have failed to pay.
The difference might reflect unpaid contributions, delayed transfers, duplicate entries, an incorrectly allocated payment, or an arithmetic error.
Establish a standard payment-recording process
A consistent process should answer four questions:
- Who made the payment?
- How much was received?
- When was the money received?
- Which contribution or obligation does the payment satisfy?
Each transaction should have an appropriate reference where possible. If a payment is entered incorrectly, the correction should be documented and authorised.
Groups evaluating Group Savings Management Software Kitengela should test how the system handles partial payments, late payments, refunds, reversals, and duplicate transactions.
Separate expected and actual collections
Expected contributions represent what members are scheduled to pay. Actual collections represent money received and verified.
These figures should not be confused. A system may show that KSh 60,000 was expected while only KSh 57,000 has been received. Both numbers are useful, but they answer different questions.
A clear dashboard can help officials identify outstanding amounts and follow up according to the group’s rules.
Avoid changing historical entries without explanation
If a treasurer corrects an old transaction, the group should be able to establish what changed, when the change occurred, and who authorised it.
An audit trail supports accountability and makes it easier to investigate discrepancies. When comparing Group Savings Management Software Kitengela options, ask whether corrections are logged rather than silently overwriting the original information.
6. Loan Administration for Table Banking and Chamas
Loan administration can become complicated when several members borrow at different times and repay under different schedules.
The group needs a reliable record of the amount borrowed, the date of disbursement, the agreed repayment terms, the applicable interest method, and every repayment received.
Record every stage of a loan
A sound loan process typically includes:
- Submission of a loan application.
- Review against the group’s lending rules.
- Approval or rejection by the authorised decision-makers.
- Documentation of the approved terms.
- Recording of the disbursement.
- Monitoring of scheduled repayments.
- Recording and reconciliation of repayments.
- Confirmation of the final balance when the loan is settled.
A group researching Group Savings Management Software Kitengela should verify that its chosen software can reflect these stages in a way that suits its governance arrangements.
Understand interest calculations
Consider a hypothetical loan of KSh 20,000. If the group’s approved policy charges simple interest of 10% on the original principal for the agreed period, the interest for that period would be KSh 2,000.
The total amount due would therefore be KSh 22,000 before any separately authorised fees or adjustments.
This example is illustrative only. Actual calculations depend on the group’s rules, the duration of the loan, repayment timing, and the agreed interest method.
Monitor overdue repayments fairly
A loan may become overdue because a member has missed a scheduled payment, a payment has not been recorded correctly, or the repayment terms have been misunderstood.
Officials should review the transaction history before taking action. Automated reminders can support consistent follow-up, but they should use respectful language and protect the member’s privacy.
For groups comparing Group Savings Management Software Kitengela, the system should distinguish overdue balances from payments that are pending reconciliation.
Prevent confusion between savings and loans
A member’s savings balance and loan obligation are different financial items. A member may have accumulated savings while also owing money under a separate loan agreement.
The group’s constitution and loan policy should determine whether and how these amounts may be offset. Software should record the arrangement accurately rather than assuming that every outstanding loan can automatically be deducted from savings.
7. M-Pesa and Digital Payment Reconciliation
Mobile money is widely used for everyday transactions in Kenya, making it a relevant consideration for savings groups. However, accepting digital payments is not the same as having automatic reconciliation.
A payment can reach the group’s account while the corresponding member record remains incomplete. Officials must still establish that the payment was received, identify its purpose, and allocate it correctly.
What to check before choosing a system
Ask prospective providers whether their product supports:
- Manual recording of mobile money payments.
- Importing transaction statements where supported.
- Payment-reference matching.
- Automated payment notifications, if available.
- Official payment integrations, where explicitly supported.
- Reconciliation reports.
- Recording of refunds and reversals.
A provider should explain which functions are included and which require additional configuration, charges, or third-party services.
Groups exploring Group Savings Management Software Kitengela should not assume that the software integrates directly with M-Pesa merely because it mentions mobile payments in its marketing.
Example of payment reconciliation
Imagine that a member sends KSh 3,000 towards a monthly contribution. The treasurer receives a transaction notification and records the payment against the member’s account.
During reconciliation, the treasurer checks the amount, date, reference, receiving account, and intended contribution period. Once verified, the payment can be marked as reconciled according to the system’s workflow.
If the reference is unclear, the payment should remain flagged for investigation until its ownership and purpose are confirmed.
Protect payment credentials
Members and officials should never share passwords, PINs, or one-time authentication codes merely to make recordkeeping easier.
Where integrations are offered, groups should understand who operates them, what permissions are granted, how credentials are protected, and how access can be revoked.
8. Financial Reporting and Accountability
Financial reports help members understand the group’s position and evaluate decisions. They are particularly important before approving new loans, making investments, distributing funds, or changing contribution amounts.
Reports that a group should consider
| Report | Main purpose |
|---|---|
| Contribution report | Shows scheduled and received contributions |
| Member statement | Summarises an individual member’s transactions |
| Loan register | Lists loans, repayment terms, and outstanding balances |
| Arrears report | Identifies overdue amounts requiring review |
| Income and expense report | Summarises financial activity during a period |
| Cash reconciliation report | Helps compare recorded transactions with actual account records |
| Investment register | Tracks group investments and related records |
| Meeting report | Presents financial information for member discussions |
A group comparing Group Savings Management Software Kitengela should prioritise reports that directly support its financial decisions rather than selecting a product simply because it produces many different charts.
Make reports understandable
Reports should use clear labels, consistent reporting periods, and understandable totals. If a figure includes unpaid amounts, it should not be presented as cash already received.
For example, a group may have KSh 500,000 in total recorded assets, but only KSh 100,000 may be readily available in its bank or mobile money accounts. The remaining value might include outstanding loans or investments.
A useful report distinguishes liquid funds from amounts tied up elsewhere.
Use financial reports during meetings
Officials can circulate appropriate summaries before meetings so that members have time to review the information.
During the meeting, the treasurer can explain significant differences, outstanding obligations, recent expenses, and proposed actions. Questions and decisions should be documented in the meeting minutes.
A system supporting Group Savings Management Software Kitengela research should be assessed on its ability to provide accurate, readable reports that can be retained as part of the group’s records.
9. Security and Privacy for Savings Groups
Savings groups handle information that deserves careful protection. Member contact details, contribution histories, loan balances, identification information, and financial transactions should not be available to everyone by default.
Role-based access
The software should allow access to be limited according to responsibilities. For example, a treasurer may need permission to record financial transactions, while an ordinary member may need only their own statement and approved group announcements.
The group should review access whenever an official changes roles or leaves the organisation.
When evaluating Group Savings Management Software Kitengela, ask how permissions are configured and whether important administrative actions can be reviewed.
Passwords and authentication
Officials should use strong, unique passwords and any additional authentication protections supported by the software. Devices used to manage the group’s finances should be protected from unauthorised access.
Shared administrator accounts should be avoided where individual accounts are available because they make it harder to establish who performed a particular action.
Data backups
A backup is useful only if the group can recover its records when needed. Ask the provider how frequently backups are created, how long they are retained, and what the recovery process involves.
The group should also understand how records can be exported and preserved independently.
Responsible handling of personal data
Kenyan organisations should consider their obligations under applicable data protection requirements, including the Data Protection Act, 2019, where relevant to their activities.
Groups should collect only the information they genuinely need, communicate how it will be used, limit access appropriately, and establish sensible retention and deletion practices. Where legal obligations are uncertain, they should seek qualified guidance.
10. How to Choose the Right Software
Selecting a system is a decision about the group’s working practices, financial controls, and long-term needs. The cheapest option is not necessarily the most suitable, and the most complex application may create unnecessary work for a small group.
Step 1: Document the group’s current process
Before contacting providers, write down how the group collects contributions, approves loans, handles expenses, records investments, and prepares reports.
Identify the most frequent problems. They might include missing receipts, late reconciliations, inconsistent interest calculations, or delays in preparing statements.
Step 2: Identify essential features
Separate essential functions from optional extras. A small group may need contribution tracking, member statements, and basic reports before it needs advanced integrations.
A larger group may require more detailed permissions, multiple contribution schedules, loan tracking, and comprehensive transaction histories.
Step 3: Compare actual demonstrations
Ask each provider to demonstrate realistic tasks using sample information. For example, request a demonstration of registering a member, recording a contribution, approving a loan, recording a repayment, and generating a report.
A provider discussing Group Savings Management Software Kitengela should be able to explain how its actual product supports the relevant tasks, rather than relying only on general claims about digital transformation.
Step 4: Confirm the total cost
Ask for a clear explanation of the pricing structure. Costs may depend on the number of members, transaction volume, selected features, implementation requirements, or subscription period.
Also ask about training, data migration, support, payment integrations, backups, and charges for additional users.
Do not assume a feature is free simply because it appears in a demonstration.
Step 5: Evaluate support and usability
Officials may have different levels of digital experience. A system should be understandable enough for the people who will use it regularly.
Ask whether training is available, which support channels are offered, what response times apply, and whether assistance is available when financial records require correction.
Step 6: Test before full implementation
Where possible, conduct a controlled trial using sample records or an approved test environment. Check calculations, permissions, reports, exports, and transaction correction procedures before moving live financial data into the system.
11. Implementation: Moving from Paper to Digital Records
A successful implementation requires preparation. Simply entering old notebook figures into a new application without checking them can reproduce existing errors in digital form.
Clean up existing records
Start by collecting the group’s current member register, contribution books, loan records, receipts, bank statements, mobile money statements, and relevant meeting minutes.
Officials should compare the records and document unresolved differences. Do not invent missing figures or treat an unverified amount as confirmed.
Agree on opening balances
The group should establish an agreed starting date for its digital records. Opening contribution balances, outstanding loans, available funds, and other relevant items should be checked and approved by the authorised officials.
Keep supporting documents so that future reviews can explain how the opening figures were established.
Train the people responsible
Training should cover routine activities and less frequent tasks, including:
- Registering and updating members.
- Recording and verifying contributions.
- Processing approved loans.
- Recording repayments and expenses.
- Generating and interpreting reports.
- Correcting mistakes appropriately.
- Protecting accounts and member information.
- Exporting and preserving records.
Introduce the system gradually
For a short, controlled transition period, the group may compare the new system’s reports against its existing records. This helps officials identify missing entries, duplicate payments, incorrect balances, and misunderstood features.
Once the records have been reconciled and the group has approved the transition, it can adopt a clearly defined process for maintaining the official digital record.
A group considering Group Savings Management Software Kitengela should also ask what assistance is available for importing existing data and resolving migration problems.
12. Common Mistakes to Avoid
Digital tools cannot compensate for unclear rules or weak financial controls. Several mistakes can undermine even a capable system.
Choosing software without defining requirements
A group may select a product because another organisation uses it, only to discover that it cannot accommodate the group’s contribution schedules or loan policies.
Document requirements before comparing providers.
Failing to reconcile transactions
A payment notification is evidence that a transaction may have occurred, but the group still needs to verify the receiving account, amount, and purpose.
Reconciliation should be a routine responsibility rather than a task postponed until the annual meeting.
Giving everyone administrator access
Unrestricted access increases the risk of accidental changes and unauthorised disclosure. Permissions should reflect responsibilities and be reviewed regularly.
Ignoring member training
Members and officials who do not understand the software may continue using informal records that contradict the official system.
Provide clear instructions and explain which record is authoritative.
Failing to keep backups
A group can lose valuable records through device failure, accidental deletion, account problems, or other incidents. Understand the provider’s backup arrangements and maintain suitable exports where permitted.
Treating automated calculations as unquestionable
Incorrect configuration can produce incorrect results. Officials should verify interest methods, repayment schedules, contribution rules, and financial reports against the group’s approved policies.
Ignoring the constitution
Software should implement the group’s legitimate rules, not replace them. Changes to contributions, penalties, lending conditions, or investment arrangements should follow the group’s governance procedures.
13. The Role of Digital Tools in Group Growth
A small group may begin with a few members and a simple savings plan. As membership grows, administration becomes more demanding.
Additional members create more payment records, more questions, more potential loan applications, and greater expectations for financial reporting. The group may also begin managing multiple projects or investment activities.
A scalable system can help the group maintain consistent processes as it grows. However, scalability should mean more than supporting a large number of member accounts. It should also mean maintaining accurate records, manageable permissions, useful reporting, and reasonable administrative effort.
Groups comparing Group Savings Management Software Kitengela should ask whether the product can accommodate their likely needs over the next few years without requiring a disruptive change of system.
Supporting investment decisions
Before committing funds to an investment, members need to understand how much money is available, which obligations remain outstanding, and what risks the proposed investment carries.
Financial records can support these discussions, but they cannot guarantee investment success. Members should evaluate opportunities carefully and obtain appropriate professional advice when necessary.
Maintaining continuity between officials
Treasurers and chairpersons may change as part of the group’s normal governance process. If financial knowledge exists only in one person’s notebooks or personal phone, the group may struggle when responsibilities change.
Shared, appropriately controlled records can make handovers easier. A departing official should transfer authorised responsibilities through a documented process, and access should be updated promptly.
14. Understanding Pricing and Value
The value of savings management software depends on the problems it solves and the effort required to maintain it.
A group should compare the total cost of a system with its practical benefits. These may include reduced time spent preparing reports, fewer calculation errors, clearer payment histories, improved reconciliation, and easier access to financial information.
Questions to ask providers
Before purchasing a subscription or service, ask:
- Is pricing based on members, users, transactions, or features?
- Is there an implementation or setup fee?
- Is training included?
- Are backups and data exports included?
- Do payment integrations require additional charges?
- What support is available, and at what cost?
- Can the group export its records if it leaves?
- Are there contract terms or cancellation fees?
- What happens to the group’s data when the service ends?
A low advertised price may exclude services the group later discovers it needs. Conversely, a premium package may contain features that the group will never use.
For groups exploring Group Savings Management Software Kitengela, the best comparison is between the total cost of ownership and the group’s documented requirements, not just the monthly subscription amount.
Consider the cost of manual administration
Officials should also estimate the time spent maintaining records, reconciling payments, correcting errors, and preparing reports.
This does not mean that software will eliminate every administrative task. It helps the group determine whether a digital process is likely to deliver meaningful value.
15. Improving Member Participation and Trust
Financial transparency is a shared responsibility. Even when the treasurer maintains accurate records, members need to understand the group’s rules and take part in its governance.
Provide regular updates
A group can agree on a reporting schedule, such as monthly contribution summaries and periodic financial reports. Updates should be distributed through appropriate channels while protecting confidential information.
Explain financial rules clearly
Members should know how contributions are calculated, how loans are approved, which interest method applies, how penalties are handled, and who can authorise expenses.
A written constitution and consistent procedures help prevent disagreements caused by different interpretations.
Give members an opportunity to ask questions
Members should be able to raise concerns about missing payments, unexpected charges, or balances they do not understand.
Officials should investigate such questions using the available records and document corrections. A transparent process can strengthen trust even when an error has occurred.
Encourage responsible participation
Digital reminders may help members remember payment dates, but reminders should support the group’s agreed procedures rather than shame individuals publicly.
When reviewing Group Savings Management Software Kitengela, consider whether its communication features allow information to be shared with the appropriate people and whether sensitive financial details can be kept private.
16. A Practical Example: A Kitengela Chama
Consider a fictional chama with 30 members. Each member agrees to contribute KSh 2,500 every month, creating expected monthly contributions of KSh 75,000.
The group also allows members to apply for loans under its written lending policy. Its officials currently use a notebook for contributions, a spreadsheet for loans, and a messaging group for announcements.
After several months, the treasurer discovers that the contribution notebook and spreadsheet do not agree. Some payments were recorded under the wrong month, and two loan repayments were entered twice.
Identifying the problem
The committee collects the available receipts, statements, contribution records, and loan documents. It compares the records, identifies duplicate entries, and confirms which payments can be verified.
Unresolved differences are documented rather than concealed.
Establishing a digital process
The group then evaluates software that can maintain member profiles, contribution schedules, loan histories, and financial reports.
It agrees on who may enter transactions, who reviews reconciliations, and which officials can approve changes. Members are shown how to review their own statements.
Reviewing the results
At the end of the next reporting period, the treasurer compares the digital records against the relevant account statements and receipts.
The group reviews its contribution collections, outstanding loans, and unresolved items during its meeting. Any corrections are documented according to the agreed process.
The main improvement is not simply having information on a screen. It is having a consistent method for recording, verifying, reviewing, and explaining financial activity.
17. Questions to Ask Before Signing Up
A product demonstration should be treated as an opportunity to test specific tasks rather than a general presentation.
Prepare a checklist and ask the provider to show how its system handles the group’s actual requirements.
Financial functionality
Can it support the group’s contribution schedules? Can it record partial payments, expenses, loan repayments, and corrections? Can it generate statements for a selected period?
Security and accountability
Can different users have different permissions? Are significant changes logged? How are backups handled? What security protections are available?
Data ownership and portability
Can the group export its member records and financial history? What happens if the subscription ends? Are there restrictions on retrieving data?
Support and implementation
What training is available? Who assists with migration? How are problems reported? Are support charges included in the quoted price?
Costs and contractual terms
What is included in the package? Which services cost extra? How can the group cancel or change its subscription?
When researching Group Savings Management Software Kitengela, use these questions to separate confirmed product capabilities from assumptions or marketing promises.
18. Frequently Asked Questions
1. What is group savings management software?
Group savings management software is a digital tool for organising activities such as member registration, contribution tracking, loan administration, payment records, and financial reporting. Available features vary by provider, so a group should check that the product supports its particular rules.
2. Can a small chama in Kitengela use savings management software?
Yes. A small chama can use a digital system if the available features, price, and training requirements suit its needs. The group should begin with essential functions and avoid paying for unnecessary complexity.
3. Does savings group software support M-Pesa?
Some systems may support manual mobile money records, transaction imports, or payment integrations. These capabilities should not be assumed. Ask the provider to demonstrate the exact integration available, including any setup requirements and charges.
4. Can software calculate interest on member loans?
A system may calculate interest when the applicable method and loan terms are configured correctly. The group should confirm whether the product supports its approved method, repayment schedules, penalties, and other relevant conditions.
5. How can software improve transparency?
It can maintain consistent transaction histories, generate financial statements, record changes, and make relevant information easier for authorised people to review. Transparency still depends on accurate entries, proper reconciliation, clear rules, and responsible governance.
6. Is group savings software suitable for table banking?
It can be suitable when the product supports the group’s contribution arrangements, loan approvals, disbursements, repayment tracking, and reporting needs. Groups should test these workflows before committing to a system.
7. How much does group savings management software cost in Kenya?
There is no single price that applies to every product. Costs may depend on membership size, features, implementation, integrations, support, and subscription terms. Request a detailed quotation and compare the total cost with the group’s requirements.
8. Can a group move its existing paper records into software?
Usually, existing information can be entered or migrated if the product supports the relevant process. Before migration, officials should reconcile historical records, document unresolved discrepancies, and agree on the opening balances.
9. How can a savings group protect its financial information?
Use strong passwords, limit access according to responsibilities, maintain appropriate backups, review account permissions, and avoid sharing confidential information unnecessarily. The group should also understand the provider’s data handling and security arrangements.
10. What should a Kitengela chama consider before choosing software?
It should consider contribution tracking, loan administration, reporting, payment reconciliation, security, ease of use, training, data exports, customer support, and total cost. A demonstration using realistic sample transactions is a practical way to compare providers.
19. Conclusion: Building Better Financial Records for the Future
Savings groups depend on trust, consistency, and a shared commitment to their financial goals. As their activities grow, maintaining reliable records becomes increasingly important. Manual methods can remain useful for simple arrangements, but they may become difficult to manage when membership, contributions, lending, and reporting requirements increase.
A suitable digital system can help organise member records, track contributions, monitor loans, improve reconciliation, and prepare clearer financial reports. Its effectiveness depends on choosing appropriate features, establishing clear responsibilities, training users, and reviewing transactions regularly.
For groups in Kitengela, the decision should begin with their actual administrative challenges. Identify the tasks that take the most time, the errors that occur most often, and the information members need to make informed decisions. Then compare available products against those requirements.
Group Savings Management Software Kitengela is the primary search term for this topic, but the software a group ultimately chooses should be evaluated on its verified capabilities, usability, security, support, and total cost. A careful selection process helps a chama or investment group build a more dependable recordkeeping system while maintaining the accountability and cooperation that make collective saving possible.
The long-term objective is straightforward: accurate records, responsible financial decisions, transparent administration, and a savings group that can continue operating confidently as its membership and ambitions evolve.
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela
Group Savings Management Software Kitengela