A Practical Guide to Smarter Savings Management for Kenyan Chamas and Investment Groups
Introduction
For a Kenyan chama, keeping track of money is only one part of running the group well. Members also need reliable records, officials need clear responsibilities, and the committee must be able to explain where contributions, loans, expenses and other funds stand. Group Savings Management Software Kenya gives savings groups a structured way to bring these activities into a digital management process instead of depending entirely on notebooks, scattered spreadsheets and WhatsApp conversations.
This guide is written for chama officials, treasurers, secretaries, chairpersons, investment groups, welfare groups, table-banking groups and other member-based organizations in Kenya. It explains what group savings software does, why manual administration becomes difficult as a group grows, which features matter most, how digital records can improve accountability, and how to choose and introduce a suitable platform. The goal is not simply to put old paperwork on a screen. It is to create a dependable system that helps a group make better decisions.
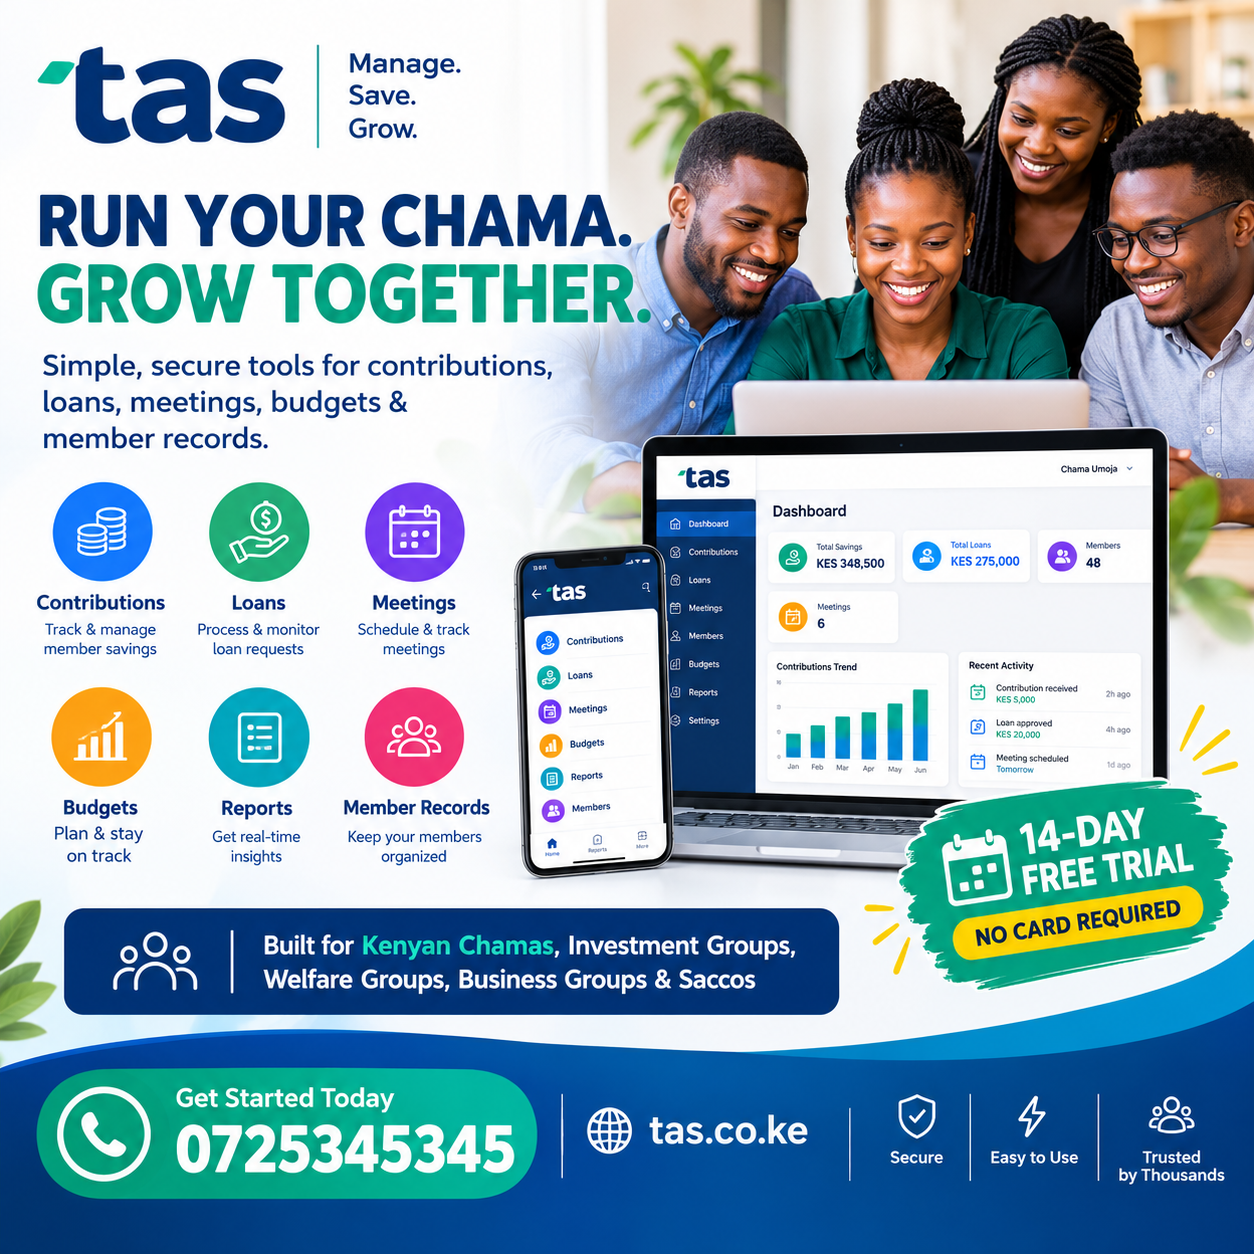
TAS is positioned specifically for Kenyan groups and describes its platform as a connected workspace for contributions, loans, meetings, budgets, reports and member records. It also states that role-based access helps keep sensitive information restricted to appropriate users.
What Is Group Savings Management Software?
At its simplest, Group Savings Management Software Kenya is software designed to organize the administrative and financial work of a savings group. Instead of keeping member details in one file, contribution records in another, loan information in a notebook and meeting information in a WhatsApp chat, a suitable platform brings related records together.
The exact features vary by provider, but a practical group savings platform may support:
- Member registration and profiles
- Savings and contribution tracking
- Welfare contributions
- Loan applications and approvals
- Loan repayment records
- Balances and outstanding amounts
- Income and expense records
- Budgets
- Meetings and minutes
- Member statements
- Financial reports
- User roles and permissions
- Data backups and exports
- Audit or activity history
The value is in the connection between these records. A member’s contribution history should not exist as an isolated number. It should be part of a wider record that helps the group understand savings performance, outstanding obligations and financial activity.
For a growing chama, Group Savings Management Software Kenya can also provide a consistent process when responsibilities move from one committee to another. The treasurer may change next year, the secretary may leave the group, or a new chairperson may take over. A system reduces the risk of the organization’s knowledge living only inside one person’s notebook or laptop.
Why Kenyan Savings Groups Need Better Record Keeping
Many chamas start informally. A few friends agree to contribute a fixed amount every month. Someone opens a notebook, another person creates a spreadsheet, and the group starts saving.
That approach is not automatically wrong. For a very small group with simple transactions, manual records may be enough for a while. The difficulty usually appears when the group becomes more active.
Suppose a group has 50 members. Some members contribute monthly savings, some contribute to welfare, several have loans, and the group also pays expenses and invests money. The treasurer is no longer recording one type of transaction. There may be several categories of money moving in different directions.
At that point, Group Savings Management Software Kenya becomes useful because it can give the committee a structured place to record and review the group’s activities.
A growing group may need to answer questions such as:
- Which members have contributed this month?
- Who has an outstanding contribution?
- How much has each member saved?
- Which loans are active?
- How much has been repaid?
- Which balances are outstanding?
- What expenses has the group approved?
- How much money is available?
- What decisions were made at the last meeting?
- Can the committee produce a clear report for members?
If answering these questions requires searching through several notebooks and spreadsheets, administration consumes time that could otherwise be spent on investment planning, member support and group development.
Manual Records Versus Digital Group Management
Manual record keeping has one major advantage: it is easy to start. A notebook costs little, and almost everyone understands how to write a transaction into it.
The problem is that a notebook does not automatically connect information. A treasurer may record a contribution on one page, a loan on another and an expense somewhere else. The secretary may maintain a different member list. If the files do not agree, the committee has to reconcile them.
A spreadsheet can improve organization, but spreadsheets still depend heavily on how they are designed and maintained. Formulas can be changed, rows can be deleted, multiple versions can circulate, and access may not be controlled carefully.
Group Savings Management Software Kenya addresses a different problem: it creates a dedicated environment for group administration.
| Manual approach | Digital group management |
|---|---|
| Paper notebooks | Centralized electronic records |
| Separate spreadsheets | Connected workflows |
| Manual calculations | Structured calculations and summaries |
| WhatsApp reminders | Organized records and workflows |
| Difficult historical searches | Searchable information |
| One-person dependency | Role-based administration |
| Reports prepared from scratch | Faster access to reports |
| Physical documents | Accessible digital records |
Digital software is not automatically better simply because it is digital. The system must match the group’s rules and processes. A complicated platform that officials cannot use confidently can create another problem. The right solution is one that improves control without making everyday administration unnecessarily difficult.
Core Feature 1: Member Management
A savings group starts with its members. If member information is inaccurate, every other process can become harder.
A useful Group Savings Management Software Kenya platform should allow the group to maintain structured member profiles. Depending on the system, the record may include a member’s name, membership status, contribution history, loan information and other details required by the group’s rules.
A central member register is particularly useful when a group has many members. The secretary does not have to maintain one list while the treasurer maintains another. The committee can work from a more consistent source of information.
Why accurate member records matter
Member records support more than administration. They help answer practical questions.
For example, if a member asks for their savings history, the responsible official should be able to locate the information without reconstructing months of transactions. If a committee is reviewing a loan application, it may need to understand the member’s existing obligations.
A structured record also helps when membership changes. New members can be added through a defined process, while members who leave can be handled according to the group’s rules.
The software should not replace the constitution or membership policy. Instead, it should help officials apply those rules consistently.
Core Feature 2: Contribution and Savings Tracking
Contribution tracking is one of the most important functions for any savings organization.
A group may collect regular savings, welfare contributions, investment contributions, special project contributions or other payments. The committee needs to know not just how much money came in, but who contributed, when the payment was recorded and what category it belongs to.
Group Savings Management Software Kenya can help organize these transactions into a clearer ledger.
For example, consider a group that expects every member to contribute KSh 5,000 each month. If there are 30 members, the expected monthly contribution is KSh 150,000. The committee can compare expected contributions with actual records and identify outstanding amounts.
The same principle works for groups with different contribution amounts. The system should reflect the group’s actual rules rather than forcing every group into an identical structure.
What contribution records should show
A useful contribution record should make it possible to identify:
- Member
- Date
- Amount
- Contribution category
- Payment status
- Relevant reference
- Running total or balance where applicable
Good records reduce arguments because the group can discuss documented transactions instead of relying on memory.
TAS publicly describes its contribution tool as a ledger for savings, welfare funds and member payments.
Core Feature 3: Loan Management
Many Kenyan chamas combine saving with member lending. Once loans are introduced, administration becomes more complex.
A loan has several stages:
- Application
- Review
- Approval or rejection
- Disbursement
- Repayment
- Balance tracking
- Completion or closure
A Group Savings Management Software Kenya platform can organize these stages and keep loan information connected to the relevant member.
The system should make it easy for authorized officials to understand how much was borrowed, how much has been repaid and what remains outstanding.
Why loan records need discipline
Loan administration is one area where unclear records can quickly damage trust.
If a member believes they have repaid KSh 40,000 while the treasurer’s spreadsheet says KSh 35,000, the committee has to investigate. If repayment dates and references are missing, resolving the disagreement becomes harder.
A structured digital record creates a stronger starting point for reconciliation.
TAS states that its loan tools cover applications, approvals, repayments and balances.
Core Feature 4: Meetings and Group Decisions
Financial administration is only one side of running a chama. Groups also make decisions.
Members may meet to approve loans, discuss investments, review expenses, elect officials, change contribution arrangements or consider new projects.
Group Savings Management Software Kenya can support the administrative side of these meetings by organizing agendas, minutes and decisions where the platform provides those features.
This matters because meeting decisions can affect financial records. If the group approves a new contribution amount, the financial process should eventually reflect that decision. If members approve an expense, the expense should have an identifiable reason and approval trail.
TAS specifically lists meeting agendas, minutes and visible group decisions among its meeting tools.
Meeting records as institutional memory
A good meeting record helps a new committee understand why a decision was made.
Without proper minutes, groups may repeatedly debate questions that were already resolved. Digital records do not eliminate disagreements, but they can provide a shared reference point.
Core Feature 5: Budgets and Expense Management
Savings groups need to control spending as carefully as they track contributions.
Expenses can include administration, meetings, banking charges, project costs, welfare support or other approved activities. The exact categories depend on the group’s constitution.
Group Savings Management Software Kenya can help a committee record income and expenses and compare spending against an approved budget.
A simple budget can answer questions such as:
- What income do we expect?
- What expenses have been approved?
- How much has already been spent?
- Which categories are above plan?
- What balance remains?
Budget visibility is especially useful when a group is saving for a major goal. If administrative expenses gradually consume money intended for investment, the members should be able to see that trend.
TAS lists budgeting, income and expenses among its group-management tools.
Core Feature 6: Reports and Member Statements
Reports turn raw transactions into information that people can use.
A treasurer may record dozens of transactions during a month. Members, however, usually need a simpler view: total contributions, expenses, loan activity, balances and the group’s overall position.
A useful Group Savings Management Software Kenya platform should provide reports that are understandable rather than merely technically detailed.
Useful reports for savings groups
Depending on the platform, useful reports may include:
- Contribution reports
- Member savings summaries
- Loan reports
- Repayment reports
- Income and expense reports
- Budget reports
- Outstanding balance reports
- Meeting records
- Member statements
Reports are particularly useful before a monthly or quarterly meeting. Instead of spending most of the meeting reconstructing figures, officials can present organized information and focus on decisions.
Core Feature 7: Transparency and Accountability
Trust is central to a savings group.
Members contribute money because they expect the group to manage it responsibly. That means financial records need to be accurate, understandable and available to the appropriate people.
Group Savings Management Software Kenya can support transparency by giving authorized users a consistent view of records.
Transparency does not mean every person should have unrestricted access to every administrative function. In fact, uncontrolled access can create its own risk.
The better approach is controlled transparency: members should be able to see information they are entitled to see, while sensitive administrative functions remain limited to responsible officials.
TAS describes role-based permissions as part of its security approach, allowing sensitive information to be restricted according to user roles.
Role-Based Access for Chamas
Different officials have different responsibilities.
A typical group might have:
Chairperson
The chairperson may need visibility into overall group activity and decisions.
Treasurer
The treasurer may handle contribution, income, expense and loan-related financial records.
Secretary
The secretary may manage member records, meetings and minutes.
Committee members
Committee members may need access to reports and approval workflows.
Ordinary members
Members may need access to their own relevant records and information shared by the group.
A Group Savings Management Software Kenya solution should allow the group to assign access according to these responsibilities.
This is more practical than giving every user the same password or unrestricted administrative rights.
Security and Data Protection
Financial and member records deserve careful protection.
When evaluating Group Savings Management Software Kenya, ask how the provider handles authentication, user permissions, backups, data access and data export. The group should also understand who can create, edit or delete records.
Security in group savings software is partly a technology issue and partly a human-behaviour issue.
Officials should:
- Use strong passwords
- Avoid sharing login credentials
- Remove access when officials leave their roles
- Review user permissions periodically
- Keep devices protected
- Verify suspicious requests
- Follow the provider’s security guidance
A platform may have strong controls, but those controls can be weakened if users share passwords or leave accounts open on public computers.
M-Pesa and Kenyan Payment Workflows
M-Pesa is a major part of everyday financial activity in Kenya, so savings groups naturally want payment records to be easy to reconcile.
When evaluating Group Savings Management Software Kenya, a group should ask exactly how payment recording works. Does the platform support direct integration? Does it allow officials to record payment references? Can transactions be matched to members? Can the group export records?
Do not assume that every platform has the same M-Pesa functionality. Payment integration should be verified during a demonstration or trial.
The objective is reconciliation. A payment should be connected to the right member and the right contribution category so that the financial record remains clear.
For a group receiving many payments, a reliable payment workflow can reduce the amount of manual data entry and checking.
Group Savings Management for Different Types of Organizations
Not every savings group operates in the same way.
A Group Savings Management Software Kenya platform can be relevant to several structures, provided its features match the group’s actual rules.
Savings chamas
A traditional savings chama may focus on regular member contributions and occasional lending.
Investment groups
An investment group may need to track contributions alongside projects, assets, expenses and investment decisions.
Welfare groups
A welfare group may collect contributions and manage member support according to agreed rules.
Table-banking groups
A table-banking group may combine contributions and lending during regular meetings.
Workplace savings groups
Employees may contribute regularly while using meetings to approve loans or group activities.
Community groups
Community organizations may combine membership records, contributions, budgets, projects and meetings.
TAS states that its platform is designed for savings chamas, investment groups, welfare groups, business groups and SACCOs/co-operatives, among other member-based organizations.
How Group Software Improves the Treasurer’s Work
The treasurer often carries a large administrative burden.
Without a structured system, they may need to:
- Record payments
- Calculate totals
- Update spreadsheets
- Check loan balances
- Prepare statements
- Reconcile transactions
- Prepare reports
- Answer member questions
- Track expenses
- Prepare figures for meetings
Group Savings Management Software Kenya can reduce fragmentation by putting related records into one workflow.
That does not mean the treasurer stops checking the figures. Financial controls still matter. Instead, the treasurer spends less time searching for information and more time reviewing whether the information is correct.
A good group savings software system should support the treasurer, not remove their responsibility.
How Group Software Helps the Secretary
The secretary is responsible for much more than taking attendance.
They may maintain the member register, prepare agendas, record minutes and keep track of decisions.
A Group Savings Management Software Kenya platform that combines financial and meeting administration can reduce the need to maintain disconnected records.
For example, when the group approves a policy change, the secretary can document the decision while the responsible financial official updates the relevant operational process.
The exact workflow depends on the platform, but the principle is important: administrative records should be organized around how the group actually works.
How Members Benefit
Digital management should not be designed only for officials.
Members are the people whose money and participation make the organization possible.
A well-designed Group Savings Management Software Kenya platform can make it easier for members to understand relevant records, follow their contributions and receive clearer information from the committee.
That can reduce unnecessary questions such as:
- How much have I saved?
- Did my contribution get recorded?
- What is my outstanding loan balance?
- What did the committee approve?
- How much has the group spent?
When information is easier to retrieve, communication can become more efficient.
Reducing Spreadsheet Dependency
Spreadsheets remain useful. They can be excellent for analysis, budgeting and ad hoc calculations.
The problem begins when the spreadsheet becomes the entire management system.
A spreadsheet can be copied. Someone can create “Final.xlsx”, then another person creates “Final Updated.xlsx”, and soon several versions exist.
Group Savings Management Software Kenya provides a more dedicated environment for operational records.
The goal of group savings software is not to declare spreadsheets useless. A group can still export information for analysis when needed. The important point is to establish one dependable source for day-to-day records.
Reducing Dependence on One Official
One of the hidden risks in manual group administration is knowledge concentration.
Imagine a treasurer who has managed the chama for five years. They know where every file is stored, understand the spreadsheet formulas and remember how several unusual transactions were handled.
If that person leaves, the group may discover that the process was never properly documented.
A Group Savings Management Software Kenya system can help distribute organizational knowledge into a structured platform.
New officials still require training, but they are not starting with an empty notebook. They can work from established records and documented processes.
This is particularly important for groups that expect leadership rotation.
Choosing the Right Group Savings Platform
There are many software options, and the most expensive or most complicated platform is not automatically the best.
Before selecting Group Savings Management Software Kenya, the committee should create a short requirements checklist.
1. Identify your group structure
Ask:
- How many members do we have?
- How often do members contribute?
- Do we issue loans?
- Do we collect welfare funds?
- Do we run investments?
- How are meetings managed?
- What reports do members expect?
2. List current problems
Do not start with features. Start with problems.
For example:
- Contribution records take too long to reconcile.
- Loan balances are difficult to calculate.
- Reports take days to prepare.
- Different officials have different spreadsheets.
- Members frequently dispute balances.
- Meeting records are difficult to retrieve.
3. Match features to problems
If the problem is loan administration, test the loan workflow. If the problem is contributions, test contribution recording and reporting.
4. Test usability
Ask officials to use the platform themselves. A system can look impressive during a sales presentation but feel confusing during everyday use.
5. Check access controls
Determine which users can view, create, edit or approve information.
6. Check data portability
Ask whether the group can export its information and what happens to the records if the subscription ends.
Questions to Ask Before Paying
A committee should not purchase Group Savings Management Software Kenya based on a feature list alone.
Ask the provider:
- How many members does the plan support?
- How many administrators can use it?
- What happens when the group grows?
- Are reports included?
- Can members view their records?
- How are loan repayments handled?
- How are contributions recorded?
- Are meeting records supported?
- How are backups handled?
- Can data be exported?
- What support is included?
- Is training available?
- Is there a trial?
- What is the total recurring cost?
- Are integrations included or charged separately?
These questions help the committee compare the real value of each option.
Cost Considerations
Price matters, especially for member-based organizations that must justify every expense.
However, the cheapest software is not necessarily the lowest-cost solution.
Suppose a committee spends several hours each month reconciling spreadsheets, correcting errors and preparing reports. That administrative burden has a cost even if no software subscription is being paid.
A Group Savings Management Software Kenya solution should therefore be evaluated using total value rather than subscription price alone.
Consider:
- Subscription cost
- Number of members supported
- Number of administrators
- Included features
- Support
- Training
- Data migration
- Integrations
- Reporting
- Backup arrangements
- Export options
TAS currently publishes plans for Kenyan chamas and offers a 14-day trial on its public website; current pricing and plan limits should always be confirmed directly before purchase because commercial terms can change.
A Practical Example: A 30-Member Chama
Consider a 30-member chama in Nairobi.
Each member contributes KSh 5,000 every month. The group therefore expects KSh 150,000 in monthly contributions before considering other transactions.
The group also:
- Provides member loans
- Collects welfare contributions
- Pays approved expenses
- Holds monthly meetings
- Produces financial reports
With paper records, the treasurer may need several pages for contributions and loans while the secretary keeps a separate member list and meeting notebook.
With Group Savings Management Software Kenya, the group can organize these activities through connected digital records, assuming the selected platform supports each workflow.
The committee can then use the monthly meeting to review results instead of spending most of the meeting reconstructing them.
The important point is not the size of the group. Even a 15-member group can benefit if its processes are becoming complicated. Conversely, a very small group with almost no transactions may not need a sophisticated platform.
A Practical Example: A Growing Investment Group
Now consider an investment group with 80 members.
Members contribute different amounts toward a long-term investment objective. The group also records expenses and discusses investment decisions during meetings.
The administration becomes more demanding because members may want to understand:
- Their contribution history
- Total group savings
- Investment-related expenses
- Group budgets
- Decisions made by the committee
- Their individual position
A Group Savings Management Software Kenya platform can provide a stronger administrative foundation when the group has the appropriate features.
The committee should still maintain sound financial controls. Software does not make an investment automatically safe or profitable. It simply improves the quality and accessibility of administrative information.
A Practical Example: Welfare Group
A welfare group may have a different objective from an investment chama.
Members may contribute a regular amount and access support when qualifying events occur.
The group therefore needs accurate membership information, contribution records and decisions about assistance.
Group Savings Management Software Kenya can help organize those records where the software supports the relevant welfare workflow.
The committee should document its eligibility rules clearly and ensure that software records reflect the group’s approved policies.
Implementation: Moving From Paper to Digital
Switching systems can feel difficult, especially when a group has years of historical records.
A gradual migration is usually easier than trying to digitize everything in one sitting.
Step 1: Clean the member list
Confirm names, membership status and other required information.
Step 2: Reconcile balances
Before importing historical financial information, agree on the correct starting balances.
Step 3: Define responsibilities
Decide who will administer members, finances, loans and meetings.
Step 4: Configure the platform
Set up the group’s categories, contribution rules and user access according to the software’s capabilities.
Step 5: Test with sample transactions
Record sample contributions, expenses and loans. Compare the results with trusted manual records.
Step 6: Train officials
Make sure the treasurer, secretary and other responsible users know their workflows.
Step 7: Go live
Choose a clear date from which the digital system becomes the main operational record.
Step 8: Review after the first month
Check for missing transactions, incorrect categories and user-access issues.
A Group Savings Management Software Kenya rollout should be treated as a process change, not simply an app installation.
Common Mistakes When Digitizing a Savings Group
Technology does not automatically solve poor processes.
Here are common mistakes to avoid.
Choosing software before defining requirements
A committee may become impressed by a long feature list without checking whether the platform solves its actual problems.
Entering incorrect opening balances
If historical balances are wrong, reports will remain wrong.
Giving everyone administrator access
Broad access makes it difficult to control changes.
Failing to train officials
A system cannot help if users do not understand how to record transactions.
Keeping several competing records forever
During migration, temporary parallel records can help with verification. But eventually the group should establish which system is authoritative.
Ignoring data export
The group should understand how it can retrieve its information.
Assuming every payment integration works the same way
Verify the exact M-Pesa or payment workflow rather than relying on assumptions.
Forgetting the constitution
Software should support the group’s approved rules, not silently replace them.
How to Build Trust Around Digital Records
Members may initially be skeptical of a new system.
Some may ask whether the figures are secure. Others may prefer the old notebook because they are familiar with it.
The committee can build confidence by introducing the system transparently.
Explain:
- Why the group is adopting it
- What problems it is intended to solve
- Who can access information
- How records will be checked
- How members can raise discrepancies
- How reports will be shared
A Group Savings Management Software Kenya implementation should make accountability easier to understand, not create a black box that only one official can access.
What Makes a Good Digital Savings System?
A strong platform should combine several qualities.
Usability
Officials should be able to complete common tasks without unnecessary complexity.
Accuracy
The system should maintain consistent records and calculations.
Security
Access should be controlled and sensitive information protected.
Reporting
The group should be able to turn transactions into useful summaries.
Flexibility
The software should accommodate the group’s actual contribution and loan rules.
Support
Users should have somewhere to get practical assistance when they encounter problems.
Accessibility
Cloud-based access can be useful for committees whose members manage the group from different locations.
TAS describes its service as accessible on any device and emphasizes secure access, backups and support for Kenyan groups.
Why Accessibility Matters in Kenya
Chama officials are not necessarily sitting in the same office every day.
Members may live in different parts of Nairobi, work in different towns or travel frequently. A system that can be accessed securely from appropriate devices can make administration more practical.
For a group with members in Nairobi, Mombasa, Kisumu, Nakuru or other counties, digital access can reduce dependence on physical documents.
However, accessibility should always be balanced with security. A group should establish responsible login practices and avoid using unsecured devices for sensitive financial work.
Building Better Financial Habits
The biggest benefit of Group Savings Management Software Kenya may not be the software itself. It may be the discipline that comes with having defined records.
When every contribution is expected to be recorded, missing transactions become easier to notice.
When loans have structured records, outstanding balances are easier to review.
When expenses are categorized, the committee can see where money is being used.
When meetings are documented, decisions are easier to revisit.
Group Savings Management Software Kenya can therefore become part of a wider improvement in group administration.
Digital Records and Leadership Transitions
Leadership changes are normal in many member-based organizations.
A new treasurer should not have to reconstruct years of transactions from handwritten notes.
A new secretary should not need to search through personal WhatsApp messages to find old meeting decisions.
A structured Group Savings Management Software Kenya platform can make organizational continuity easier because important information remains associated with the group rather than an individual’s personal files.
Before a leadership transition, the outgoing officials should still conduct a proper handover, verify records and review user access.
When Software May Not Be Necessary
It is also important to be realistic.
Not every group needs software immediately.
A small group with very few transactions, a stable membership and simple administration may be comfortable with a well-maintained spreadsheet.
The question is whether Group Savings Management Software Kenya would make the current system more reliable and sustainable.
A group should consider dedicated software when manual administration starts causing problems such as:
- Frequent reconciliation errors
- Lost records
- Slow report preparation
- Confusion over member balances
- Difficult loan tracking
- Poor visibility into expenses
- Heavy dependence on one official
- Increasing membership
- Multiple financial activities
Group Savings Management Software Kenya should solve a real problem rather than become an unnecessary expense.
Why TAS Is Relevant to Kenyan Chamas
TAS presents itself as a platform built for Kenyan groups rather than a generic tool adapted from an unrelated business process.
Its public platform currently highlights contributions, loans, meetings, budgets, reports and secure access. It also lists savings chamas, investment groups, welfare groups, business groups and SACCOs/co-operatives among the types of groups it supports.
For a group considering Group Savings Management Software Kenya, this type of specialization can be worth evaluating because the software should reflect how member-based organizations actually operate.
TAS also provides a trial option, allowing a group to explore the platform before committing.
A Checklist for Your Committee Meeting
Before approving any software, bring these questions to the committee.
Operations
- What processes currently consume the most time?
- Which records are most difficult to maintain?
Finance
- How are contributions recorded?
- How are loans tracked?
- How are expenses approved?
Membership
- How many members do we have?
- How quickly are we growing?
Reporting
- Which reports do members need?
- How often are they prepared?
Security
- Who should access financial records?
- How will former officials lose access?
Technology
- Do officials have suitable devices and internet access?
- Is training available?
Cost
- What will the software cost over one year?
- What support and features are included?
These questions make the buying process more objective.
Frequently Asked Questions
What is group savings management software in Kenya?
Group Savings Management Software Kenya refers to digital software used to organize the administration and financial activities of Kenyan savings groups. Depending on the platform, it can cover members, contributions, loans, repayments, meetings, budgets, expenses and reports.
Can a chama use group savings management software?
Yes. A chama can use a suitable platform to organize contribution records, member information, loans, meetings and financial reporting. The software should be tested against the chama’s actual constitution and workflows before adoption.
Does group savings software replace a treasurer?
No. It supports the treasurer’s work; it does not replace financial responsibility. Officials still need to verify transactions, approve activities according to the group’s rules and review reports.
Can group savings software manage loans?
Many group-management platforms include loan workflows. Before purchasing, confirm whether the system supports the specific loan process your group uses, including applications, approvals, repayments, balances and any guarantor rules.
Can group savings software track contributions?
Yes, contribution tracking is a core use case. A suitable platform should allow the group to record payments and review individual or group contribution history.
Is group savings software useful for investment groups?
It can be. Investment groups need member records, contributions, expenses, meetings and reporting, and digital administration can organize those activities. Investment decisions themselves still require proper governance and financial analysis.
Should a small chama buy group savings software?
It depends on complexity. A small group may manage effectively with a spreadsheet, but software becomes more valuable when membership, transactions, loans or reporting requirements increase.
How should a chama choose software?
Start by documenting the group’s current processes and problems. Then compare platforms based on member capacity, contribution management, loan workflows, reports, permissions, data export, support, usability and total cost.
Is M-Pesa integration important for Kenyan savings groups?
It can be useful, particularly for groups receiving many payments. However, committees should verify exactly what a provider’s M-Pesa functionality includes instead of assuming that every platform has direct integration.
Conclusion
A savings group becomes harder to manage when its financial activities grow faster than its record-keeping processes. Members may still trust one another, but trust works best when it is supported by clear records, defined responsibilities and transparent reporting.
Group Savings Management Software Kenya offers a practical way to organize contributions, member records, loans, meetings, budgets and reports in a structured digital environment. The best results come when software is combined with clear group rules, responsible financial controls, proper approvals and regular review.
For Kenyan chamas and savings organizations, the decision should not be based only on having an attractive dashboard. Evaluate the real workflow. Test how contributions are recorded. Test loan administration. Check reports. Review user permissions. Ask how data can be exported. Consider the support available. Most importantly, involve the people who will actually use the system every month.
TAS is specifically positioned for Kenyan groups and currently offers tools covering the core areas many chamas need, including contributions, loans, meetings, budgets, reports and secure role-based access.
If your group has reached the point where notebooks, spreadsheets and scattered messages are taking too much time to reconcile, it may be the right moment to test a dedicated platform. The goal is simple: cleaner records, clearer accountability and more time for members to focus on saving, investing and building the future of their group.
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya
Group Savings Management Software Kenya