Chama Treasurer Software Kenya: A Complete Guide to Better Group Financial Management
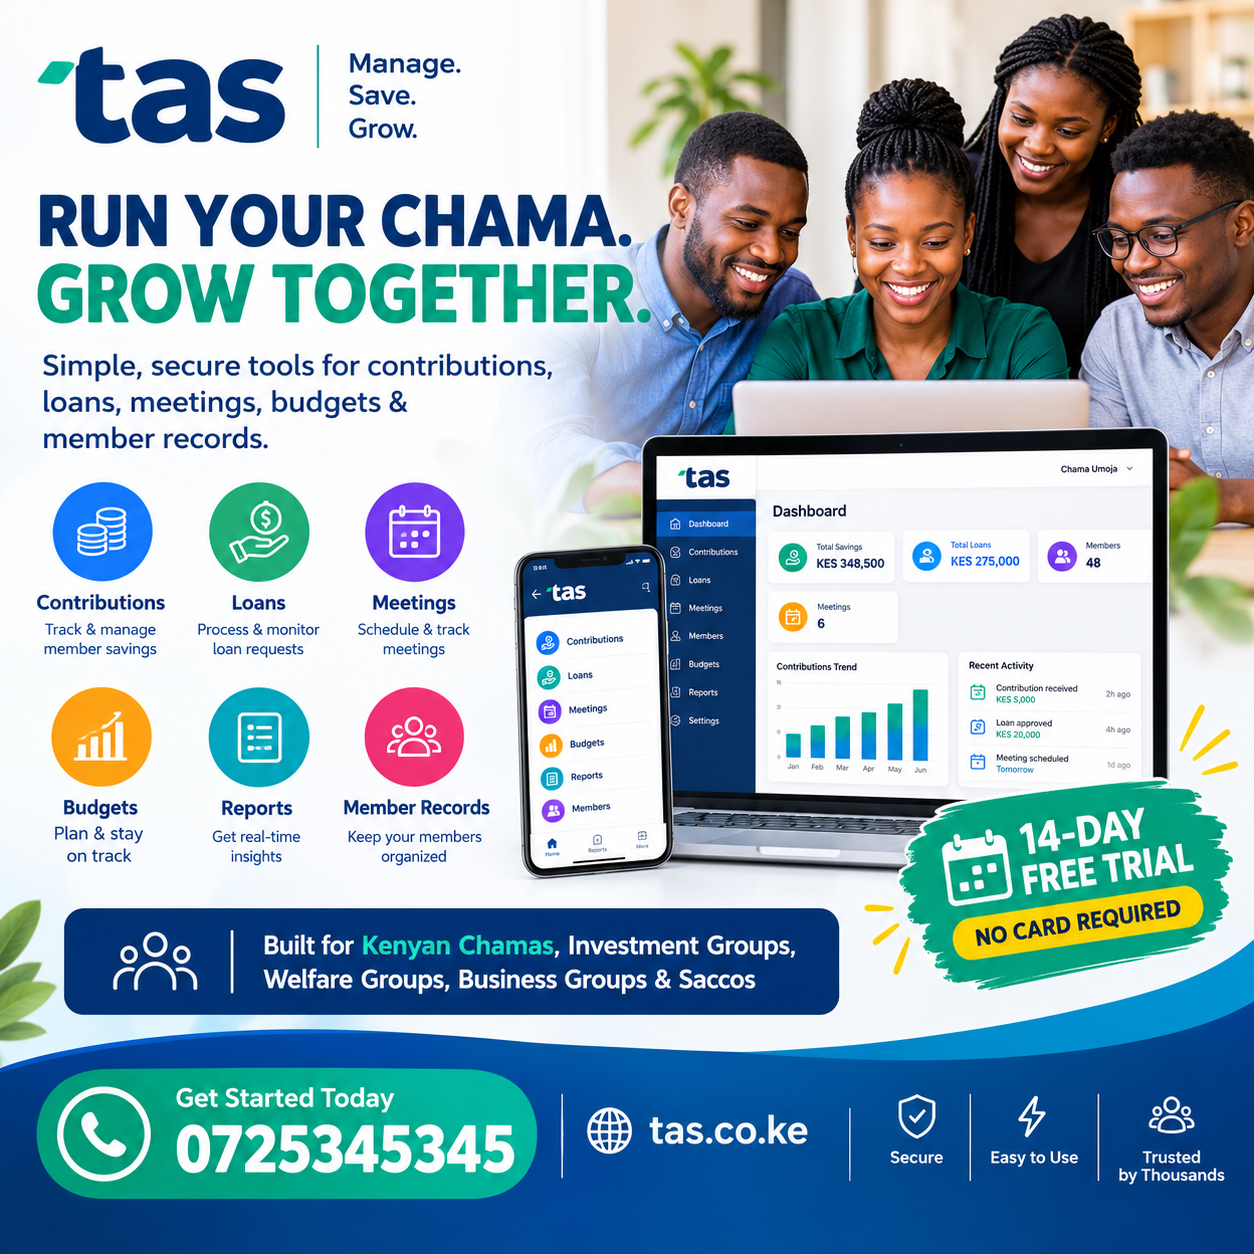
Chama Treasurer Software Kenya: A Complete Guide to Managing Chama Finances
Managing money is one of the most important responsibilities in any chama. Members contribute their hard-earned income with the expectation that their savings will be recorded correctly, loans will be monitored, and financial decisions will be transparent. For a treasurer handling dozens of members, several payment channels, and multiple financial activities, manual record-keeping can become difficult. Chama Treasurer Software Kenya provides a useful starting point for understanding how digital financial management can help groups improve their records, accountability, and day-to-day operations.
A chama may begin with a simple notebook, a spreadsheet, and a mobile money transaction history. These tools can work when the group is small and transactions are limited. However, as membership grows and activities become more complicated, the treasurer must manage contribution schedules, outstanding loans, interest calculations, bank balances, expenditure approvals, and financial reports. Small errors can create disagreements that affect the entire group.
Digital chama management offers a more organised way to handle these responsibilities. Instead of depending entirely on handwritten records or scattered messages, a group can use a central system to record transactions, review balances, monitor payments, and prepare reports.
This guide explains what chama treasurer software is, why Kenyan investment groups may need it, which features matter most, and how a chama can introduce digital financial management without disrupting its existing activities. It also explores common mistakes, security considerations, implementation steps, and questions members should ask before choosing a solution.
1. Understanding Chama Treasurer Software
A chama treasurer is responsible for helping maintain accurate financial records and ensuring that the group’s money is managed according to its rules. Depending on the group, these duties may include collecting contributions, documenting expenses, tracking loans, preparing reports, and presenting financial information during meetings.
Chama Treasurer Software Kenya refers to digital tools that can help treasurers organise these responsibilities more efficiently. Depending on the solution selected, the system may support member registration, savings records, payment tracking, loan administration, expense recording, and financial reporting.
The goal is not simply to replace paper with a computer. It is to establish a reliable process through which every financial transaction can be recorded, checked, and explained.
What does chama treasurer software do?
A suitable system can help a group:
- Maintain a register of members and their financial details.
- Record regular savings and special contributions.
- Monitor members who have paid, underpaid, or missed contributions.
- Track loans issued to members and repayments received.
- Calculate outstanding loan balances using approved rules.
- Record approved expenses and withdrawals.
- Compare recorded transactions with bank and mobile money statements.
- Generate financial summaries for meetings.
- Maintain a history of transactions for future reference.
The exact features vary between software products. A chama should confirm that its chosen platform supports its particular contribution arrangements, lending rules, reporting requirements, and approval procedures.
Who benefits from this type of software?
The most obvious user is the treasurer, but the benefits can extend across the group.
The chairperson may need financial summaries before approving a proposal. The secretary may need attendance records and meeting resolutions. Members may want to confirm their contributions or outstanding loan balances. An auditor or designated reviewer may need to inspect transaction histories.
A central record system can make these tasks easier without requiring every member to have unrestricted access to the group’s entire financial database.
2. Why Kenyan Chamas Need Better Financial Records
Chamas in Kenya operate in different ways. Some focus on table banking, others accumulate savings for investments, and others contribute towards land purchases, property development, education, or emergency assistance.
The financial processes that suit a small welfare group may not be sufficient for an investment club managing substantial contributions and multiple loans.
Chama Treasurer Software Kenya can help groups understand how digital record-keeping may address common administrative challenges, provided the chosen platform includes the necessary functions.
Managing frequent member contributions
Members may contribute weekly, monthly, quarterly, or according to an agreed schedule. Some groups also collect registration fees, welfare contributions, penalties, or special investment payments.
When these amounts are recorded in different notebooks or spreadsheets, the treasurer may struggle to produce one accurate statement for each member.
A central contribution register can show the expected amount, the amount received, the transaction date, and any remaining balance. This makes it easier to identify discrepancies before they become serious problems.
Reducing disputes over money
Financial disagreements sometimes begin with simple questions: Was a contribution received? Was a loan repayment recorded? Was a withdrawal approved? How much interest has accumulated?
Without reliable records, members may depend on screenshots, memory, or old meeting notes.
Chama Treasurer Software Kenya illustrates the type of digital solution a group might investigate when looking for clearer transaction histories and more consistent financial reporting.
A digital record does not automatically prevent fraud or eliminate disputes. Its value depends on accurate entries, appropriate access controls, supporting documents, and regular reconciliation.
Supporting groups with growing membership
As a chama grows, the number of transactions and member enquiries often increases. A treasurer who previously handled ten members may eventually need to manage fifty or more.
At that point, manual calculations can consume time that would otherwise be spent reviewing investment opportunities, following up on overdue payments, and planning group activities.
Software can reduce repetitive administration by organising information and producing summaries from recorded transactions.
Improving confidence in financial leadership
Members are more likely to understand their group’s financial position when reports are consistent and transactions can be traced.
The treasurer should be able to explain the opening balance, contributions received, loans issued, repayments collected, expenses paid, and closing balance.
Good records support informed decisions and make leadership transitions easier when a new treasurer takes office.
3. Essential Features to Look For
Not every chama needs an elaborate financial platform. The right choice depends on the group’s size, financial activities, internal controls, budget, and technical experience.
Chama Treasurer Software Kenya is a useful search phrase for exploring the broader category of software solutions, but a group should evaluate actual product features rather than choosing a system based on its name alone.
Member registration and profiles
The software should allow authorised users to maintain a reliable register of members.
Useful fields may include:
- Member number or unique identifier.
- Name and approved contact information.
- Membership status.
- Date of joining.
- Contribution arrangements.
- Applicable membership category.
- Relevant account balances.
Sensitive personal information should be collected only when necessary. The chama should also define who can view, update, or export member records.
Contribution tracking
Contribution management is one of the most important functions for a treasurer.
The system should allow the group to define its contribution schedule and record each payment against the appropriate member and obligation.
For example, a group may require every member to contribute KSh 5,000 per month. If a member pays KSh 3,000, the system should record the amount received and show the remaining KSh 2,000, assuming the group’s rules permit partial payments.
It should also distinguish between a payment that has been promised, one that has been received, and one that has been confirmed against the relevant bank or mobile money statement.
Loan management
A chama that lends money to members needs accurate loan records.
Important information includes the principal amount, disbursement date, repayment schedule, approved interest method, payments received, penalties where applicable, and outstanding balance.
The system should apply the rules approved by the group rather than relying on assumptions about interest rates or repayment periods.
Expense and withdrawal records
Money leaving the group’s account should be documented clearly.
A good expense register can capture the amount, date, purpose, beneficiary, approving authority, and supporting receipt or invoice.
Where the group’s procedures require multiple approvals, the software should support an appropriate review process or provide a way to document approval before the transaction is finalised.
Financial reporting
A treasurer should not have to recalculate every figure whenever members request an update.
Reports may include contribution summaries, loan balances, outstanding payments, expenditure statements, cashbook entries, and monthly or annual financial summaries.
Chama Treasurer Software Kenya is another example of the phrase being used to explore digital management options, but the specific platform must be checked for chama-related reporting features before adoption.
4. How Contribution Tracking Works in Practice
Consider a chama with 20 members who each contribute KSh 5,000 every month.
The expected monthly contributions are:
20 members × KSh 5,000 = KSh 100,000.
If all members pay the full amount, the group expects to collect KSh 100,000. If two members miss their payments and another contributes only KSh 2,500, the actual total is KSh 87,500.
The difference between the expected and actual amounts is KSh 12,500.
Without a structured register, the treasurer might have to inspect several payment messages and manually calculate each member’s position. A digital system can present the expected amounts, recorded payments, and outstanding balances in one place.
Tracking different contribution categories
Some groups have several financial obligations at the same time.
For example, members may contribute KSh 5,000 towards savings, KSh 500 towards welfare, and an additional amount towards a specific investment.
These payments should not be combined indiscriminately. Each contribution should be assigned to the correct category so that the treasurer can explain how the money was intended to be used.
A well-organised register helps the group distinguish general savings from funds reserved for a particular purpose.
Handling late and partial payments
A group should agree on how late payments are handled before configuring its software.
The rules should explain whether partial payments are allowed, when a payment becomes overdue, whether penalties apply, and who can approve an exception.
Chama Treasurer Software Kenya can be used as part of a wider keyword research and digital management discussion, while the chama should confirm that its selected financial platform can accommodate the required payment rules.
Producing member statements
A member statement should make it easy to understand the transactions affecting an individual’s position.
Depending on the group’s arrangements, it may show the opening balance, contributions received, loan disbursements, repayments, approved charges, and closing balance.
Statements should identify the period covered and the date on which they were generated. Members should have a clear process for raising questions if they believe a transaction is missing or incorrect.
5. Loan Administration and Repayment Monitoring
Many chamas use member savings to provide loans. These loans can support business activities, education, emergencies, and other agreed purposes.
However, lending creates additional responsibilities. The group needs to document approvals, record disbursements, calculate repayments correctly, and monitor outstanding obligations.
Chama Treasurer Software Kenya can help frame the search for digital tools, but loan-related capabilities must be confirmed directly with the software provider.
Recording a loan application
A loan process may begin with a member submitting a request that states the amount required, purpose, preferred repayment period, and any supporting information required by the group.
The application should then pass through the chama’s agreed approval procedure.
The record should distinguish between an application, an approved loan, and money actually disbursed. An approval alone should not automatically be treated as a completed payment.
Calculating repayments
Suppose a chama approves a loan of KSh 30,000. The group agrees that the member will repay the principal in six equal monthly instalments without interest.
The monthly principal repayment would be:
KSh 30,000 ÷ 6 = KSh 5,000.
If the group charges interest, the calculation changes according to the agreed method. A reducing-balance arrangement, for example, differs from a flat-rate arrangement.
The treasurer should configure the correct approved method and ensure that the repayment schedule is communicated clearly to the borrower.
Monitoring outstanding loans
A loan register should identify how much has been issued, how much has been repaid, and what remains outstanding.
It should also show upcoming repayment dates and overdue amounts where applicable.
This helps the treasurer prepare accurate reports and enables the committee to address repayment problems early, following the group’s policies.
Handling early repayment and restructuring
Members may occasionally wish to repay a loan early or request a revised schedule.
The chama should document its rules for these situations. The treasurer should not independently change repayment terms unless authorised to do so.
A digital system should preserve the original agreement and document approved changes so that the transaction history remains understandable.
6. Improving Transparency and Accountability
Financial transparency means members can understand how the group receives, holds, lends, spends, and reports money.
It does not mean every member must have unrestricted access to every sensitive record. Instead, members should receive the information they are entitled to see through an agreed reporting process.
Chama Treasurer Software Kenya fits into a broader discussion of digital solutions that can support organised administration, although the suitability of any product for financial reporting should be verified.
Maintain a transaction history
Every financial entry should identify the transaction date, amount, category, relevant member or beneficiary, and any supporting reference.
Corrections should be documented rather than silently overwriting the original record. Where the software supports an audit trail, authorised reviewers can see who made a change and when it occurred.
Separate recording from approval
Where practical, the person entering a transaction should not be the only person authorised to approve it.
For example, the treasurer may record a proposed expense while the chairperson or another authorised officer verifies the supporting documents and approves payment according to the group’s rules.
This division of responsibility reduces the risk of errors and inappropriate transactions going unnoticed.
Prepare reports before meetings
Members should not have to wait until a meeting begins to discover the group’s financial position.
The treasurer can prepare reports in advance, allowing members to review contribution totals, outstanding loans, expenses, and planned commitments.
Questions can then focus on specific transactions or decisions instead of trying to reconstruct the entire financial history.
Reconcile records regularly
A software balance is only as reliable as the information entered into the system.
The treasurer should compare the recorded transactions with actual bank statements, mobile money statements, cash receipts, and other relevant evidence.
Differences should be investigated and resolved through a documented process.
7. Managing M-Pesa and Other Payment Methods
Mobile money is a familiar payment method for many Kenyan groups. Members may also use bank transfers, cash deposits, or other approved channels.
The main challenge is ensuring that every payment is recorded accurately and assigned to the correct member and contribution category.
Chama Treasurer Software Kenya can be part of a wider search for digital business tools, but a chama should specifically verify whether a candidate platform supports the payment methods it uses.
Recording M-Pesa payments
A treasurer may receive payment confirmations from members or review an official transaction statement.
Each payment should be matched against the correct member, amount, date, and contribution obligation.
Where a group uses an automated integration, it should confirm how transactions are imported, whether matching is automatic or manual, and how unmatched payments are handled.
Understanding the difference between recording and receiving money
A member’s screenshot or message may help identify a transaction, but it should not automatically replace confirmation from the relevant payment record.
Similarly, entering a payment into software does not itself move money into the chama’s bank or mobile money account.
The group should distinguish between recording a transaction and confirming that the funds were actually received.
Handling unidentified payments
Sometimes money arrives without a clear member reference.
The treasurer should place the transaction under an appropriate pending or unidentified category, investigate its source, and assign it to a member only after verification.
This avoids crediting the wrong person or counting the same payment twice.
Confirming integration capabilities
Before purchasing software, ask the provider whether the platform offers a genuine payment integration, a manual statement import, or only a facility to record payments.
These are different capabilities and may have different costs and security implications.
8. Cashbooks, Expenses, and Financial Reconciliation
A cashbook provides a chronological record of money received and money paid out. For a chama, it is an essential tool for understanding changes in the group’s financial position.
Chama Treasurer Software Kenya can be used to frame research into digital administration, but a group should select a platform that specifically supports its cashbook and reconciliation needs.
Recording money received
Receipts may include member contributions, loan repayments, approved income from investments, and other amounts earned or received by the group.
The treasurer should record each receipt under the correct category and retain an appropriate transaction reference.
Recording expenses
Payments may include approved administrative costs, bank charges, investment expenses, or other group expenditure.
Each expense should have a clear purpose and supporting evidence where appropriate.
A description such as “payment” is less useful than a specific explanation of what was purchased or paid for.
Calculating the closing balance
The basic cashbook calculation is:
Opening balance + money received − money paid out = closing balance.
Suppose a chama starts the month with KSh 250,000. It receives KSh 100,000 in contributions and KSh 20,000 in loan repayments. It pays KSh 15,000 in approved expenses and disburses KSh 50,000 in loans.
The expected closing balance is:
KSh 250,000 + KSh 100,000 + KSh 20,000 − KSh 15,000 − KSh 50,000 = KSh 305,000.
The treasurer should compare this calculated balance with the actual balances held in the relevant accounts and any cash held by the group.
Investigating discrepancies
If the records show KSh 305,000 but the verified account balance is KSh 300,000, the KSh 5,000 difference should be investigated.
Possible explanations include a missing transaction, a duplicate entry, a bank charge, an incorrectly recorded amount, or a transaction that has not yet cleared.
The treasurer should not simply adjust the software balance to make the figures match. The underlying reason should be established and documented.
9. Financial Reports That Help Members Make Decisions
Reports turn individual transactions into information that members can use when deciding what the chama should do next.
A useful report should be accurate, understandable, and relevant to the decision being discussed.
Chama Treasurer Software Kenya can serve as a keyword anchor in the article’s wider digital-management context; actual reporting functions must be assessed on the specific platform.
Monthly contribution reports
These reports can show expected contributions, actual receipts, and outstanding amounts for each member.
The treasurer can use them to follow up on unpaid contributions and confirm whether the group has collected enough money for its planned activities.
Loan portfolio reports
A loan report should show outstanding principal, repayment progress, overdue instalments, and upcoming repayment dates where relevant.
This allows the committee to understand how much money remains tied up in loans and whether the group has sufficient funds for upcoming obligations.
Income and expenditure reports
These reports summarise money received and money spent during a selected period.
The group should ensure that the categories are consistent from one reporting period to the next. Otherwise, comparisons may be misleading.
Investment performance reports
A chama that owns land, property, shares, or another investment may need reports beyond its routine cashbook.
Such reports should distinguish cash held by the group from the estimated value of its investments. An increase in estimated asset value is not necessarily cash available for withdrawal or lending.
Reports for annual reviews
An annual report can help members assess contribution performance, lending activity, expenditure, investment commitments, and the quality of the group’s financial controls.
The figures should reconcile with the underlying records and be accompanied by explanations of significant changes.
10. Security and Protection of Member Information
Chama records may contain names, telephone numbers, payment histories, loan details, identification information, and other sensitive information.
Protecting these records is part of responsible financial management.
Chama Treasurer Software Kenya is included here as a linked keyword destination, but groups should independently assess the privacy and security arrangements of whichever platform they consider.
Use role-based access
Not every user needs permission to edit every record.
The treasurer may need to record transactions, while the chairperson may need approval permissions and ordinary members may only need access to their own statements or approved group reports.
Access should reflect each person’s actual responsibilities.
Require strong authentication
Users should protect their accounts with strong, unique passwords and use multifactor authentication where available.
Shared accounts make it difficult to establish who performed a particular action. Each authorised user should have an individual account whenever the platform supports it.
Check backups and recovery
The chama should ask how often the system is backed up, how data can be restored, and what happens if a device is lost or an account becomes inaccessible.
It should also maintain an appropriate export or backup process that does not unnecessarily expose members’ personal information.
Understand data ownership
Before signing up, the group should clarify who controls its financial records, how records can be exported, what happens when a subscription ends, and how data can be deleted or retained when appropriate.
If the provider experiences an outage, the chama should understand what records remain accessible and what recovery arrangements exist.
Review privacy obligations
Groups handling personal information should consider their responsibilities under Kenya’s applicable data protection framework, including the Data Protection Act, 2019, where relevant.
They should collect only necessary information, restrict access appropriately, and understand how the provider stores and processes data.
11. Choosing Software for a Small or Large Chama
A small welfare group and a large investment club do not necessarily need the same features.
The selection process should begin with the group’s real requirements rather than an assumption that the most expensive or complicated platform is the best.
Chama Treasurer Software Kenya provides another linked phrase for this article, but the group should evaluate available products against a written list of requirements.
Small chamas
A small group may prioritise member registration, contribution tracking, basic expense records, and simple financial reports.
The platform should be easy to learn and affordable relative to the group’s resources.
Medium-sized investment groups
A growing group may need more detailed loan administration, member statements, transaction approvals, recurring contribution schedules, and stronger reporting.
It may also need support for multiple officers with different permissions.
Large or complex groups
A group with several investment projects, substantial lending activity, or multiple branches may require more advanced reporting, detailed audit trails, flexible account structures, and integration with existing financial processes.
Before choosing such a platform, the group should confirm that the additional complexity will provide practical value.
Create a feature comparison
The committee can compare candidate systems using a simple checklist.
| Requirement | Questions to ask |
|---|---|
| Member records | Can the platform maintain a complete member register? |
| Contributions | Can it handle regular and special contributions? |
| Loans | Can it apply the group’s approved loan rules? |
| Expenses | Can payments be linked to approvals and supporting documents? |
| Reporting | Can it generate clear member and group reports? |
| Payments | Does it support the payment methods the chama uses? |
| Security | Are individual accounts and suitable access controls available? |
| Backups | Can data be restored or exported? |
| Support | Is training and technical assistance available? |
| Cost | What are the full subscription, setup, and transaction costs? |
12. Understanding the Cost of Chama Software
The cost of a digital system should be assessed against its usefulness, reliability, and long-term affordability.
Some products may charge a monthly or annual subscription. Others may use a one-time payment, a transaction-based fee, or a package that combines different services.
Chama Treasurer Software Kenya appears here as a linked anchor in the prescribed rotation; its presence does not imply that it provides chama software or that any particular pricing is available.
Look beyond the advertised price
The total cost may include:
- Initial setup or configuration.
- Data migration from notebooks or spreadsheets.
- Training for the treasurer and committee.
- Monthly or annual subscriptions.
- Payment integration charges.
- Additional user accounts.
- Technical support.
- Data exports or other optional services.
Ask the provider to explain all charges before committing.
Calculate the cost per member
Suppose a chama has 40 members and a software subscription costs KSh 2,000 per month.
The monthly cost per member is:
KSh 2,000 ÷ 40 = KSh 50.
The annual subscription would be KSh 24,000, before any additional charges.
The group can compare this cost with the time saved, the quality of its records, and the importance of reliable reporting. It should not assume that software will automatically produce a financial return.
Consider affordability and continuity
The group should choose a payment arrangement it can sustain.
If the subscription is likely to become unaffordable, the committee should understand whether it can export its records and transition to another system without losing essential information.
A clear exit plan is part of responsible software selection.
13. How to Introduce Software Without Disrupting the Chama
Changing from notebooks or spreadsheets to a digital system requires planning. Members need to understand what is changing, who is responsible, and how existing records will be preserved.
Chama Treasurer Software Kenya can anchor this discussion of digital tools, while the actual implementation should be based on the features of the chosen chama platform.
Step 1: Review existing records
Before entering data, gather the current member register, contribution records, loan schedules, bank statements, outstanding balances, and relevant meeting resolutions.
Identify missing information and unresolved discrepancies.
Do not assume that every historical figure is correct simply because it appears in a notebook.
Step 2: Agree on financial rules
The committee should document the contribution schedule, loan interest method, repayment terms, approval limits, expense procedures, and reporting frequency.
The software should reflect the rules approved by the group.
Step 3: Select a responsible administrator
The chama should designate who will manage user accounts, enter opening balances, and maintain the records.
Other officers should review the information according to the group’s internal controls.
Step 4: Enter and verify opening balances
Opening balances must be based on reliable records.
For example, the group should distinguish its available bank balance from money lent to members, unpaid contributions, and other financial assets.
If the total recorded position does not reconcile, investigate the difference before relying on the new system.
Step 5: Test typical transactions
Before full adoption, test routine activities such as recording a contribution, receiving a loan repayment, approving an expense, and generating a monthly report.
Confirm that the system produces the expected results.
Step 6: Train the officers
The treasurer, chairperson, secretary, and relevant reviewers should understand their responsibilities.
Training should include correcting errors, protecting accounts, exporting records, and preparing reports.
Step 7: Review the first reporting period
At the end of the first month, compare the digital records with the original transaction evidence.
Resolve discrepancies, collect feedback, and adjust procedures where necessary.
14. Common Mistakes to Avoid
Even a capable software platform cannot compensate for poor financial practices.
The chama should establish clear procedures and ensure that the people using the system understand them.
Chama Treasurer Software Kenya can be used to connect this discussion to the website’s intended topic, but the software’s actual features should be confirmed directly.
Entering transactions without evidence
A transaction should have a reliable basis, such as an official payment record, receipt, bank statement, or approved financial instruction.
Where supporting evidence is temporarily unavailable, the record should be flagged for verification rather than treated as unquestionable.
Failing to reconcile accounts
Recording payments is only one part of financial management.
The treasurer must compare recorded amounts with actual funds and investigate differences. Reconciliation should occur regularly rather than only when a member raises a complaint.
Giving one person unlimited control
Allowing one person to record, approve, and reconcile every transaction creates unnecessary risk.
Where practical, the group should separate responsibilities and require another authorised officer to review significant payments.
Ignoring overdue loans
A loan balance may remain outstanding for months if nobody monitors repayment dates.
The chama should use a clear follow-up procedure that is fair to borrowers and consistent with the group’s approved policies.
Failing to protect access credentials
Sharing passwords through group chats or using a single account for every officer weakens accountability.
Access should be removed promptly when an officer leaves their role.
Choosing software without testing it
A demonstration may not reveal every limitation.
Before making a commitment, test the tasks the treasurer performs most often and ask how the platform handles errors, corrections, backups, and data exports.
15. Practical Example: A Chama Managing Savings and Loans
Imagine a chama called Tumaini Investment Group with 30 members. Each member contributes KSh 4,000 per month, and the group occasionally lends money to members under approved repayment arrangements.
The expected monthly savings contribution is:
30 × KSh 4,000 = KSh 120,000.
During one month, all members pay their contributions. The group receives KSh 15,000 in loan repayments and issues KSh 40,000 in new loans. It also spends KSh 5,000 on approved administrative expenses.
Assuming no other transactions, the net increase in the group’s cash balance is:
KSh 120,000 + KSh 15,000 − KSh 40,000 − KSh 5,000 = KSh 90,000.
This calculation describes the change in cash, not the full financial position of the group. The newly issued loan is still an amount owed to the chama, while repayments reduce the outstanding loans.
Chama Treasurer Software Kenya can be used as the next linked anchor in the requested rotation while the example illustrates why accurate categorisation matters.
What should the treasurer record?
The treasurer should record the 30 contributions individually, the loan repayments against the relevant borrowers, the new loan disbursements, and the approved expenses.
The supporting records should include payment references and evidence of the loan approvals and expense authorisation.
What should the monthly report show?
The report should distinguish between:
- Savings contributions received.
- Loan repayments received.
- New loans issued.
- Administrative expenses.
- Available cash and bank balances.
- Outstanding loans.
- Any unpaid contributions or overdue repayments.
This information gives members a clearer understanding of what happened during the month and how much money is available for future commitments.
What happens if a member disputes a payment?
The treasurer should review the recorded entry alongside the relevant payment evidence.
If the payment is confirmed but was assigned to the wrong member, the correction should be documented. If it cannot be verified, the treasurer should explain what evidence is missing and follow the group’s dispute-resolution process.
The aim is to resolve the issue using records rather than assumptions.
16. The Role of the Treasurer Beyond Record-Keeping
A treasurer does more than enter figures into a register. The role involves helping the group understand its finances and make decisions based on reliable information.
Chama Treasurer Software Kenya is linked here as part of the requested rotation, while the broader lesson is that digital tools should support sound financial leadership rather than replace it.
Planning cash requirements
The treasurer should understand upcoming obligations, including expected expenses, scheduled loan disbursements, and commitments to investment projects.
A contribution report may show how much money is expected, but the group must still assess whether those funds will arrive in time to meet its commitments.
Supporting investment decisions
Before committing money to a new investment, members should understand how much cash is available, which funds are reserved for existing obligations, and what risks the proposed investment carries.
The treasurer can provide financial information to support this discussion, but investment decisions should follow the group’s governance procedures.
Preparing for leadership changes
When a new treasurer takes over, the group should complete a documented handover.
The handover may include account balances, outstanding loans, contribution records, financial reports, pending transactions, authorised signatories, and access permissions.
Digital records can make this process easier when they are complete, accurate, and accessible to authorised officers.
17. Evaluating Software Providers Before Making a Decision
A chama should evaluate both the product and the organisation providing it.
A polished demonstration does not automatically establish that a system is suitable, secure, or dependable.
Chama Treasurer Software Kenya provides another anchor in the specified sequence, but provider evaluation should rely on verified product information.
Ask for a practical demonstration
Request a demonstration using realistic examples.
Ask the provider to show how to register a member, record a contribution, correct an error, enter a loan repayment, record an expense, and produce a financial report.
This reveals more than a general presentation of the interface.
Check the support arrangements
Ask what happens if the treasurer cannot access the account, a report appears incorrect, or a transaction has been recorded twice.
Clarify support hours, available communication channels, response expectations, and whether training is included.
Confirm ownership and portability
The chama should be able to understand how it will obtain its records if it changes providers.
Ask whether records can be exported in a usable format, whether transaction histories are retained, and whether the group can access its information when a subscription ends.
Review the terms and limitations
The group should read the relevant terms of service, pricing conditions, privacy information, and any limitations on user accounts or transaction volumes.
Claims about security, integrations, or regulatory compliance should be supported by clear documentation.
18. Building a Long-Term Financial Management Process
Successful digital adoption depends on consistent habits, not merely on installing software.
The chama should establish a routine that covers transaction entry, verification, reporting, and review.
Chama Treasurer Software Kenya can be linked within this wider discussion, while the practical objective is to build a process that remains reliable even when the group’s officers change.
Daily or transaction-based responsibilities
The treasurer should record financial transactions promptly, retain supporting evidence, and flag unclear payments for verification.
Delaying entries increases the risk of omissions and makes it harder to reconstruct what happened.
Weekly responsibilities
Where transaction volumes justify it, the treasurer can review recent receipts, unpaid contributions, pending approvals, and upcoming loan repayments.
Regular checks help identify problems before they accumulate.
Monthly responsibilities
At the end of each reporting period, the treasurer should reconcile relevant accounts, review outstanding balances, prepare financial reports, and communicate important discrepancies to the appropriate officers.
The group should document the review process and record decisions made in response to the reports.
Annual responsibilities
An annual review can assess whether the software continues to meet the group’s needs, whether user permissions remain appropriate, and whether the financial procedures are working as intended.
The group should also review subscription costs, backup arrangements, and its ability to retrieve records if it changes providers.
19. Frequently Asked Questions
1. What is chama treasurer software?
It is a digital tool designed to help a chama manage financial records. Depending on the platform, it may support member contributions, loans, repayments, expenses, account balances, and financial reports. The group should confirm that the software supports its specific financial arrangements before adopting it.
2. How can a treasurer track monthly chama contributions?
The treasurer can maintain a register showing each member’s expected contribution, the amount received, the payment date, and any outstanding balance. A suitable digital system can organise these records and generate summaries, but entries should still be verified against reliable transaction evidence.
3. Can chama software help manage member loans?
Yes, where the platform includes loan management. It may record applications, approvals, disbursements, repayment schedules, interest, and outstanding balances. The treasurer should confirm that the software supports the chama’s approved lending rules and does not impose an unsuitable calculation method.
4. Can a chama use software to track M-Pesa payments?
That depends on the chosen platform. Some systems may offer an integration, while others may require manual entry or statement imports. The chama should confirm exactly how transactions are received, matched to members, verified, and corrected when discrepancies occur.
5. Is digital financial management suitable for a small chama?
Yes. Even a small group can benefit from organised member records, consistent contribution tracking, and clear financial reports. However, the chosen system should be affordable, easy to use, and proportionate to the group’s actual needs.
6. How much does chama treasurer software cost in Kenya?
Pricing varies by provider, features, subscription model, and transaction arrangements. A chama should request a current quotation and consider setup, training, support, integration, and recurring charges in addition to the advertised price. Avoid assuming that a specific price applies without confirmation from the provider.
7. How can a chama protect its financial records?
The group should use individual user accounts, strong passwords, appropriate permissions, reliable backups, and regular reconciliations. It should also restrict access to sensitive member information and establish a process for removing former officers from the system.
8. Can software prevent fraud in a chama?
Software can improve traceability, document approvals, and make discrepancies easier to investigate. It cannot eliminate fraud on its own. Effective protection also requires independent reviews, separation of responsibilities, reliable transaction evidence, and consistent enforcement of the group’s financial rules.
9. What should a chama check before choosing software?
The committee should evaluate contribution tracking, loan management, expense records, reporting, payment support, security, data exports, customer support, and total cost. A practical demonstration using the group’s actual workflows can help reveal whether the platform is suitable.
10. How can a new treasurer take over digital records?
The group should prepare a formal handover covering opening balances, outstanding loans, unpaid contributions, recent reconciliations, pending transactions, reports, and authorised account access. The incoming treasurer should verify the records with another authorised officer before assuming responsibility.
20. Conclusion: Better Records Support Better Chama Decisions
A chama depends on trust, consistent contributions, responsible lending, and clear financial decisions. When records are scattered across notebooks, messages, and spreadsheets, the treasurer may spend too much time checking figures and answering repeated questions.
Digital financial management can provide a more structured approach to recording contributions, monitoring loans, documenting expenses, reconciling accounts, and preparing reports. However, the best results come when software is combined with clear rules, verified transactions, appropriate access controls, and regular financial reviews.
For Kenyan investment groups, the selection process should begin with the actual responsibilities of the treasurer. Identify the group’s challenges, agree on the required features, compare available solutions, test realistic transactions, and confirm the provider’s costs and support arrangements.
Chama Treasurer Software Kenya is the central search phrase for this article because it reflects the specific need for digital tools that support chama treasury responsibilities. Before selecting any particular platform, verify its features and suitability rather than relying on the keyword or general marketing claims.
Ultimately, the purpose of digital chama management is straightforward: help the treasurer maintain dependable records, help members understand their financial position, and give the group a stronger foundation for making informed decisions.
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya
Chama Treasurer Software Kenya