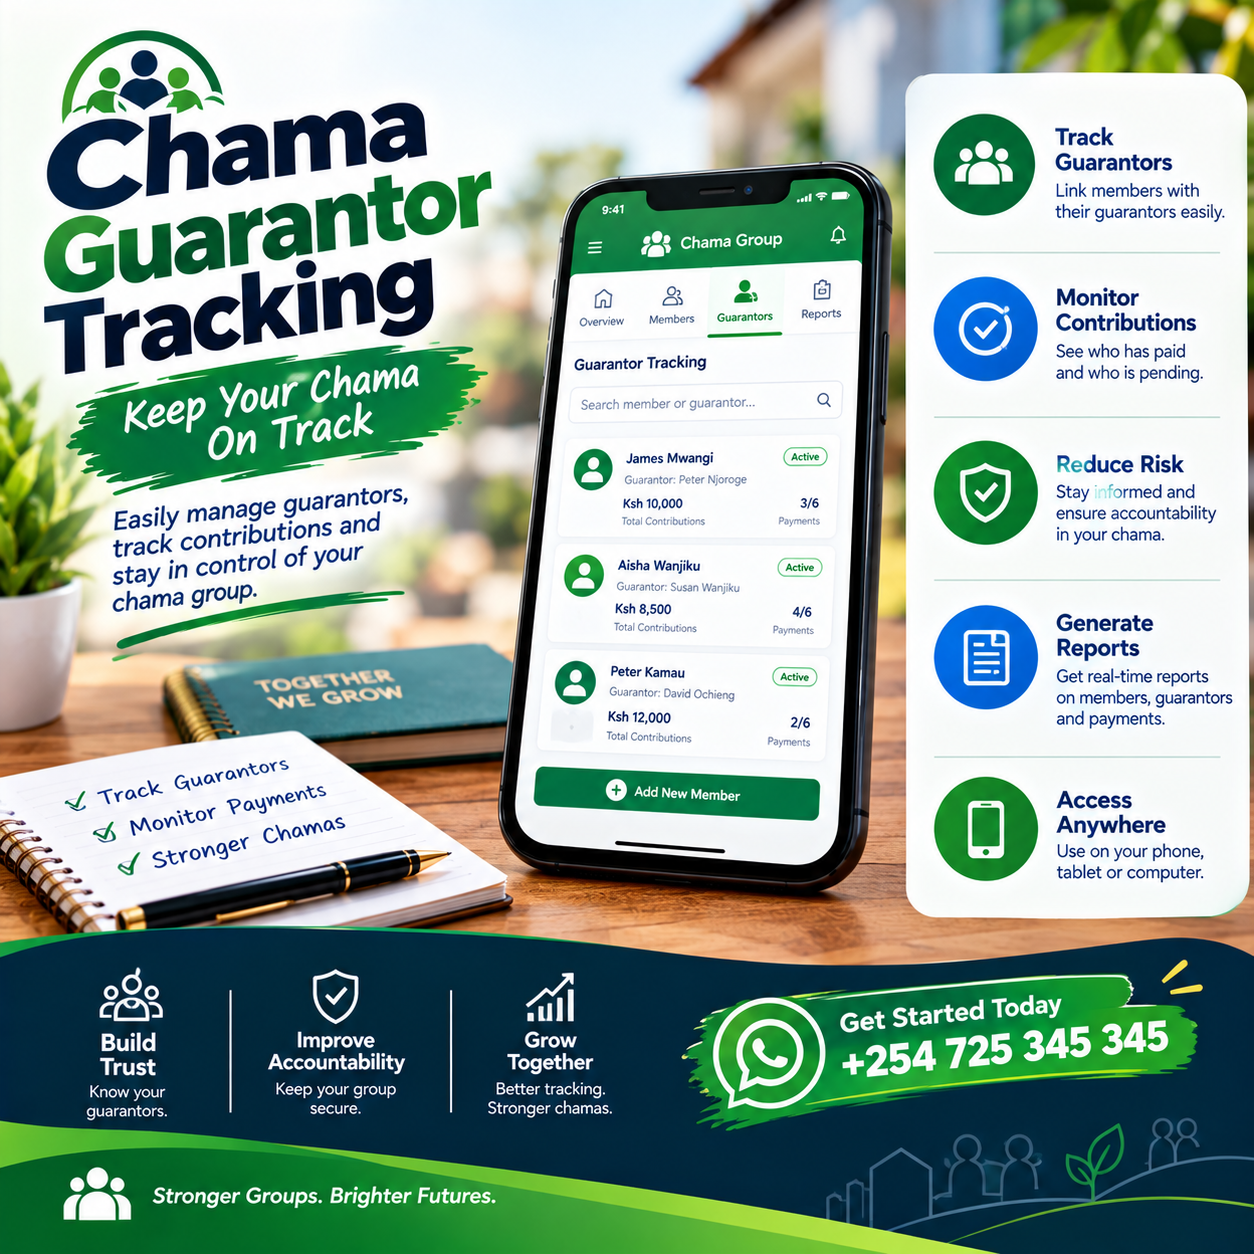
Chama guarantor tracking is the quiet discipline that separates lending groups that thrive from those that slowly bleed capital and friendships. In nearly every Kenyan chama, before a member borrows, trusted friends must stand behind the loan with their own savings. Managing those promises well is what this complete guide to chama guarantor tracking is all about.
Every shilling a group lends is protected — or exposed — by the guarantees standing behind it. When a borrower struggles, the guarantor becomes the group’s safety net, and clarity about that role becomes priceless. That is precisely why serious groups invest in chama guarantor tracking from their very first loan.
The trouble is that most groups treat guarantees as a formality. A name is scribbled on a loan form, filed away, and forgotten until the day it is needed. By then, the weaknesses of skipping chama guarantor tracking have already done their damage.
This guide changes that entirely. It explains what guarantees really mean, how to monitor exposure across your whole portfolio, and how digital tools make the work effortless. By the end, chama guarantor tracking will feel like a natural habit rather than an administrative burden.
The article is written for treasurers who keep the loan book, chairpersons who approve loans, and members who are asked to guarantee. It is equally written for borrowers who deserve to understand what they are truly asking of their friends. Everyone touched by chama guarantor tracking benefits from seeing the full picture.
One truth deserves stating upfront. Guarantees are not signatures on paper — they are real commitments of real savings. Groups that honor that reality through chama guarantor tracking almost never suffer the guarantee disputes that tear others apart.
The good news is that this discipline is simple. It needs only clear rules, visible records, and consistent review — none of which cost money. Modern platforms have made chama guarantor tracking as easy as checking a balance on a phone.
So read this guide with your loan book open beside you. Tick the practices your group already follows, and note the ones worth adding. The calmest time to strengthen chama guarantor tracking is today, long before the next difficult conversation arrives.
What Is a Guarantor in a Chama?
A guarantor is a member who pledges their own savings, shares, or deposits to secure another member’s loan. If the borrower fails to repay, the guarantor’s pledged amount becomes the group’s recovery path. Understanding that chain of responsibility is the starting point of chama guarantor tracking.
The role is deeply cultural as much as it is financial. In Kenyan groups, standing as a guarantor is a statement of trust between friends who have saved side by side for years. That human warmth is exactly why chama guarantor tracking must always be handled with care and dignity.
Guarantees come in different shapes. Some are full guarantees covering the entire loan, while others are partial, with several members sharing the risk. Recording which type applies to each loan is a foundational task of chama guarantor tracking.
There are also joint guarantors, where two or more members pledge together. When recovery becomes necessary, the group must know exactly who owes which share. Precision here is one of the core promises of chama guarantor tracking.
Some groups also allow self-secured lending against a member’s own deposits. Technically that removes the guarantor, but the pledged deposits still need monitoring. A complete approach to chama guarantor tracking covers self-secured loans too.
What a guarantor is not matters just as much. A guarantor is not a villain-in-waiting, and a borrower is not free to default because someone else stands behind them. Setting that respectful tone is part of the culture that chama guarantor tracking builds over time.
Why Guarantor Tracking Matters So Much
The first reason is protection of group capital. When guarantees are tracked, the group always knows how much of its loan book is genuinely secured. That visibility is the core financial value of chama guarantor tracking.
The second reason is protection of guarantors themselves. A member can quietly accumulate five guarantees across different loans without realizing they have pledged more than their savings. Preventing that silent overcommitment is a central duty of chama guarantor tracking.
The third reason is faster, fairer recovery. When a loan goes bad, a group with clear records moves within days instead of arguing for months. Speed backed by evidence is what chama guarantor tracking delivers at the worst possible moments.
The fourth reason is better lending decisions. Officials who can see a borrower’s full guarantor history approve new loans with far richer information. Smarter approvals are a quiet dividend of chama guarantor tracking.
The fifth reason is trust among members. Guarantors who can see their own exposure anytime feel respected rather than trapped. That confidence is the social reward of chama guarantor tracking.
The sixth reason is dispute prevention. Most guarantee conflicts begin with two honest people remembering the same promise differently. Written, visible records are the antidote, and that is the everyday work of chama guarantor tracking.
The seventh reason is portfolio health. Groups can spot dangerous concentrations — one popular member guaranteeing half the loan book — before they become crises. Risk mapping is the strategic layer of chama guarantor tracking.
The eighth reason is succession. When treasurers change, guarantee records that live in the system transfer cleanly with everything else. Continuity like that is a lasting gift of chama guarantor tracking.
The True Cost of Poor Guarantor Tracking
Now for the honest part, because the costs of neglect are real. Groups that fail to monitor guarantees routinely discover phantom coverage — names on forms whose owners never truly agreed. Every phantom guarantee is a hole that chama guarantor tracking would have caught at signing.
The second cost is overexposed members. When a crisis hits one borrower, three or four untracked guarantors can be dragged down together. Cascading losses are the signature disaster that chama guarantor tracking prevents by design.
The third cost is slow recovery. Without records, recovery conversations start with archaeology instead of action. Months of delay are the price groups pay for skipping chama guarantor tracking.
The fourth cost is human. Friendships strain when a guarantor learns of their obligation only at the recovery stage. Surprise, more than money, damages relationships — and surprise is exactly what chama guarantor tracking removes.
The fifth cost is cultural. Once one member is burned by a forgotten guarantee, nobody volunteers to guarantee again. Frozen lending is the long-term wound that chama guarantor tracking avoids entirely.
The sixth cost shows up at the AGM. Loan books presented without guarantee coverage invite hard questions that officials cannot answer. Credibility in front of the whole membership is another quiet return on chama guarantor tracking.
Key Features of Effective Guarantor Tracking
Effective tracking rests on a handful of capabilities. Use the checklist below to evaluate how your group manages guarantees today. Each feature addresses a failure mode described in the sections above.
Feature 1: The Guarantor Register
Every guarantee should live in a structured register, not on scattered loan forms. The register records who guaranteed whom, for how much, on which loan, and on what date. A living register is the foundation of all chama guarantor tracking.
Feature 2: The Exposure Dashboard
Officials should see total guarantee exposure per member at a glance. One screen should answer how much each member has pledged and how much remains active. That single view is the operational heart of chama guarantor tracking.
Feature 3: Verified Consent
No guarantee should exist without the guarantor’s confirmed, recorded agreement. Digital confirmations, witnessed signatures, or documented verbal approvals all leave permanent trails. Verified consent is the integrity layer of chama guarantor tracking.
Feature 4: Automatic Notifications
Guarantors should be told when their guarantee is activated, when repayments lag, and when the loan closes. Silence between signature and crisis is where most damage breeds. Timely alerts are the communication engine of chama guarantor tracking.
Feature 5: Release Management
As a borrower repays, the guarantor’s exposure should shrink automatically. When a loan closes, the guarantee should be formally released and visibly marked as done. Watching exposure fall is one of the most satisfying outcomes of chama guarantor tracking.
Feature 6: Portfolio Reports
Officials need quarterly views of total guarantees outstanding, coverage ratios, and concentration risks. Reports turn individual entries into strategic intelligence for the whole group. Portfolio-level insight is the leadership dimension of chama guarantor tracking.
Feature 7: Member Self-Service
Guarantors should see their own commitments on their phones, anytime, without asking the treasurer. Self-service visibility dissolves suspicion faster than any meeting explanation. Personal dashboards are the trust feature of chama guarantor tracking.
Feature 8: Complete Audit Trails
Every change to a guarantee — creation, adjustment, release, or activation — should be logged with dates and names. When memories differ a year later, the trail settles the matter in seconds. Permanent records are the legal backbone of chama guarantor tracking.
How to Set Guarantor Rules in Your Constitution
Rules are where tracking begins, so write them before the next loan is issued. Begin by defining who may act as a guarantor in your group. Clear eligibility is the first pillar of chama guarantor tracking.
Most groups require guarantors to be fully paid-up members with savings equal to a set share of the loan. Some add tenure requirements, so only seasoned members can carry large guarantees. Whatever you choose, write it plainly into the framework of chama guarantor tracking.
Second, set exposure limits. A common rule caps total active guarantees at the guarantor’s own savings, or at a fixed multiple of them. Enforced limits are the protective core of chama guarantor tracking.
Third, require a consent ceremony for every guarantee. The guarantor confirms the amount, the loan purpose, and their obligation in front of an official or through the platform. That moment of informed agreement is the dignity standard of chama guarantor tracking.
Fourth, define guarantor rights explicitly. Guarantors should be entitled to see the loan’s repayment status and to be notified of any arrears. Balanced rights and duties are what make chama guarantor tracking feel fair to everyone.
Fifth, write the release conditions. State clearly when a guarantee ends — final repayment, loan restructuring, or committee approval — and how the release is recorded. Clean endings are the finishing discipline of chama guarantor tracking.
Sixth, prepare the dispute path. If a guarantor contests an obligation, the constitution should define who hears the case and how it is resolved. A predetermined path is the safety net inside chama guarantor tracking.
Finally, review the rules annually at the AGM. Lending volumes grow, savings levels change, and limits deserve recalibration from time to time. Living rules are what keep chama guarantor tracking effective year after year.
The Guarantee Lifecycle: Stage by Stage
Every guarantee travels through six stages, and each stage generates records worth keeping. Understanding the journey helps officials track guarantees as living commitments rather than static signatures. This lifecycle view is the practical engine of chama guarantor tracking.
Stage 1: The Request
The journey begins when a borrower asks a fellow member to guarantee. The request should state the amount, the term, and the repayment plan in writing. Clarity at the request stage is the first checkpoint of chama guarantor tracking.
Stage 2: Verification and Consent
Before any signature, the group verifies that the guarantor has the savings and the clean standing required. Consent is then recorded formally, with the amount and date captured in the register. Verified beginnings are what make later stages of chama guarantor tracking effortless.
Stage 3: Active Monitoring
While the loan runs, the guarantor’s exposure sits visible on the register and the dashboard. Repayment progress is tracked, and guarantors receive updates or alerts when instalments slip. Live visibility is the day-to-day heartbeat of chama guarantor tracking.
Stage 4: Repayment Progress
As instalments land, the outstanding balance falls and the guarantor’s exposure falls with it. Many groups share this progress with guarantors as encouragement that the end is in sight. Shrinking exposure is the rewarding middle phase of chama guarantor tracking.
Stage 5: Release
When the final instalment clears, the guarantee is formally released in the records. The guarantor’s capacity is restored automatically, ready for the next time a friend needs help. Clean releases are the closure milestone of chama guarantor tracking.
Stage 6: Recovery — When Things Go Wrong
If the borrower defaults, the documented guarantee becomes the group’s recovery path. Recovery follows the constitution exactly, with amounts, shares, and dates already on record. Orderly outcomes under pressure are the ultimate test of chama guarantor tracking.
Tools: From Notebooks to Digital Platforms
Paper registers served groups for generations, and they still beat nothing at all. A simple book can list each guarantee with amounts and dates, updated after every meeting. But paper is where most groups hit the limits of manual chama guarantor tracking.
Spreadsheets improve the arithmetic but inherit familiar weaknesses. Formulas break silently, versions multiply, and one official’s laptop holds the group’s memory hostage. Those fragilities are precisely what push growing groups toward digital chama guarantor tracking.
Dedicated platforms transform the entire experience. Exposure dashboards update in real time, guarantors receive automatic alerts, and releases post themselves as loans close. Automation at that level is the modern standard of chama guarantor tracking.
When evaluating any platform, bring a real guarantee to the demo. Watch it record a consent, track repayments, shrink the exposure, and release the guarantee end to end. A system that performs that journey will carry your chama guarantor tracking faithfully for years.
Common Mistakes to Avoid
The first classic mistake is collecting signatures without verifying capacity. A guarantor with empty savings is a comfort blanket, not a guarantee. Capacity checks are the first discipline of chama guarantor tracking.
The second mistake is letting one popular member carry too much. When half the loan book rests on one trusted soul, the group has built a single point of failure. Concentration limits are the protective wisdom of chama guarantor tracking.
The third mistake is never telling guarantors anything. Silence between signature and crisis breeds both resentment and surprise. Communication discipline is the relationship-saving habit of chama guarantor tracking.
Real Stories from Kenyan Groups
The Nakuru teachers’ chama once discovered that three loan forms carried guarantor signatures nobody could verify. Rebuilding trust took months, and lending was suspended while the group sorted fact from memory. The rebuilt register now sits at the center of their chama guarantor tracking, and no loan moves without verified consent.
The Kitengela landlords’ group faced a genuine default and recovered smoothly. Because their platform showed every guarantee’s amount, date, and share, recovery completed within weeks and without a single shouted argument. The committee credits their chama guarantor tracking with saving both the money and the friendships.
Across the country, the pattern repeats with striking consistency. Groups with visible guarantee records lend more confidently, recover faster, and keep members volunteering to stand for one another. That quiet confidence is the true product of disciplined chama guarantor tracking practiced year after year.
Frequently Asked Questions
How much can one member safely guarantee?
A common and prudent ceiling is the guarantor’s own savings, with some groups allowing up to double for long-standing members. Whatever you choose, enforce it in the system so limits apply automatically. That single rule carries most of the value in chama guarantor tracking.
Should guarantors be notified when repayments fall behind?
Yes, always — early awareness lets guarantors encourage the borrower while the problem is still small. Silence only manufactures the surprise that damages friendships. Prompt alerts are a defining habit of professional chama guarantor tracking.
Can a guarantee be partial, shared among several members?
Absolutely, and shared guarantees spread risk sensibly across the group. Just record each person’s exact share so recovery, if ever needed, follows the book. Clear shares are a core record inside chama guarantor tracking.
What happens to a guarantee if the borrower repays early?
The guarantee should be released immediately, restoring the guarantor’s full capacity. Early release recorded visibly is one of the happiest moments in chama guarantor tracking.
Do guarantors earn anything for the risk they carry?
Some groups credit guarantors with a small share of loan interest or formal recognition at the AGM. Others treat guaranteeing as a duty of membership, which is equally valid. Whichever culture you choose, make it visible through your chama guarantor tracking records.
Can a member refuse a guarantee request without damaging friendships?
Yes, and healthy groups normalize the polite no. A member near their exposure limit has every right — and often a duty — to decline. Respecting limits is precisely what chama guarantor tracking makes possible.
How do we handle a guarantor who is also struggling financially?
Treat it like any exposure review — restructure the underlying loan, adjust the guarantee, and document everything with committee approval. Compassion with paperwork is the mature expression of chama guarantor tracking.
We also own rental units — should guarantees apply there too?
Property lending deserves the same discipline, and the smartest groups keep the two ecosystems connected. Group loans and guarantees run on the chama platform, while tenants, rent collection, and owner statements run on Tas.co.ke. One clean, connected view of everything the group owns is the full promise of chama guarantor tracking.