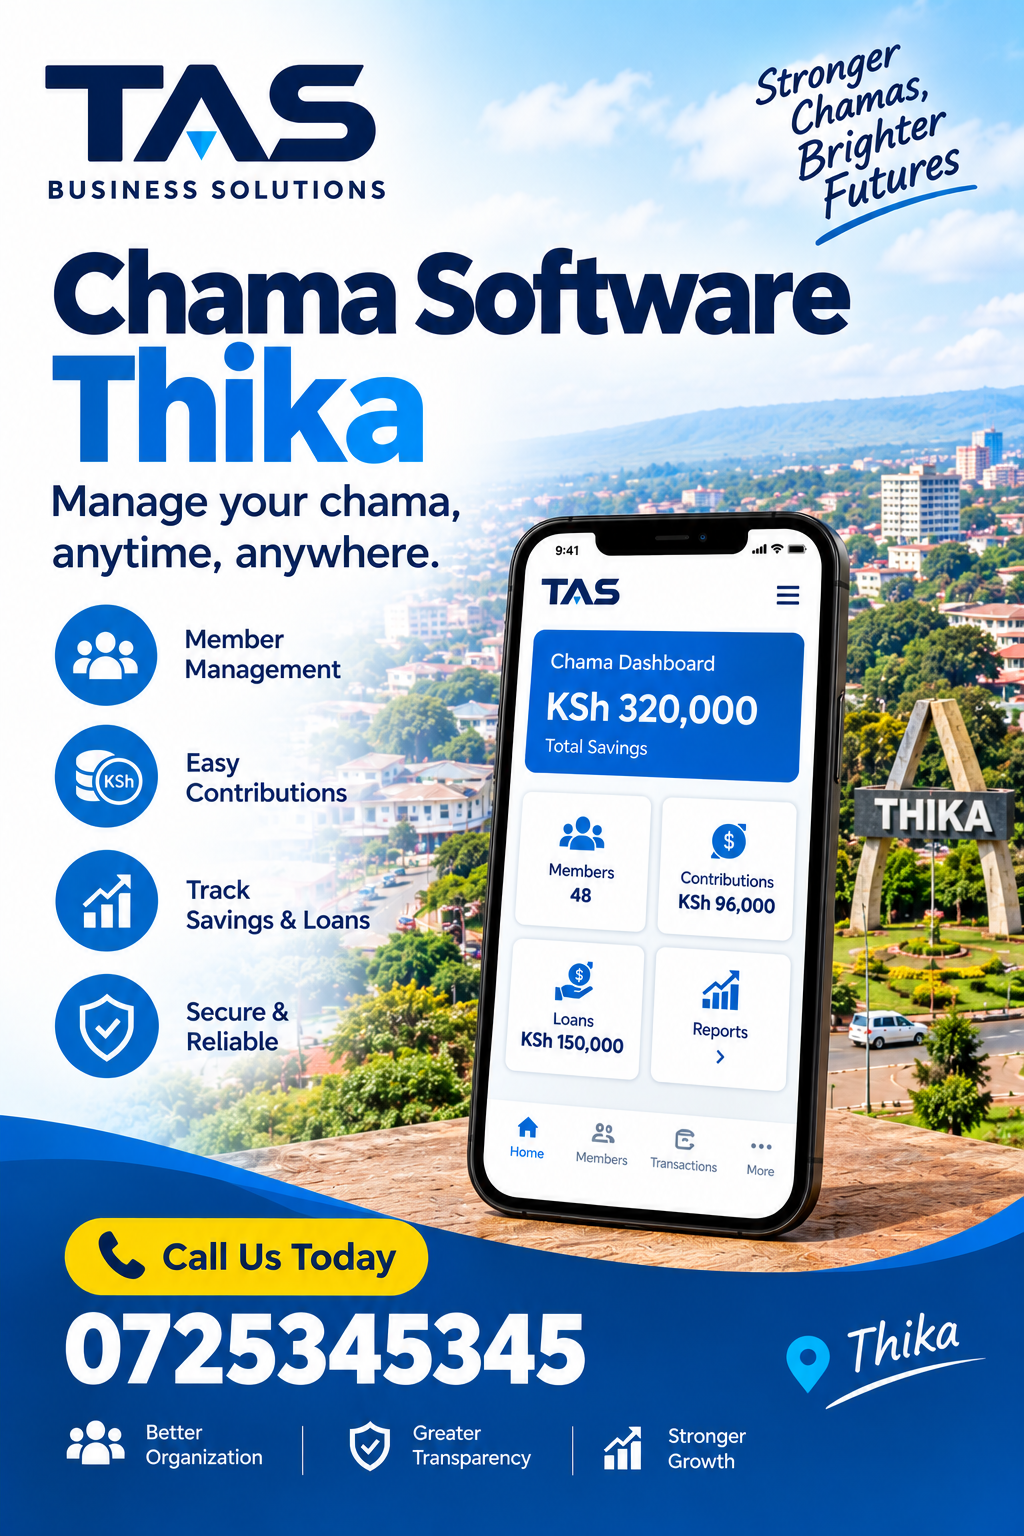
A Practical Guide to Chama Management in Thika
Managing a chama in Thika can become difficult when member contributions, loans, meetings, welfare records and investment decisions are spread across notebooks, WhatsApp messages and personal spreadsheets. Chama Software Thika gives chama officials and members a structured way to organize these activities in one place. This guide explains what chama management software should do, the problems it can solve for groups in Thika, the features worth prioritizing, and how a group can introduce a digital system without disrupting its existing operations.
Understanding chama management in Thika
Chamas in Thika can have very different purposes. Some groups focus on monthly savings, while others invest in land, property, businesses, farming projects or other income-generating activities. Welfare groups may collect regular contributions and support members during emergencies. Investment groups may handle larger amounts and require stronger records, approvals and reporting. Chama Software Thika is most useful when it reflects the actual rules and workflow of the group rather than forcing every chama into one generic structure.
A small group may begin with a notebook because there are only a few members and transactions are limited. As membership grows, however, the record-keeping burden increases. A treasurer may need to confirm who paid, when payment was received, how much was outstanding and whether the money was allocated to savings, welfare, a loan or an investment fund. Chama Software Thika can help turn those recurring administrative tasks into a consistent process.
The Thika business environment also creates opportunities for organized groups. Members may live in Thika, Juja, Ruiru, Kiambu or nearby areas while working in different sectors. Meetings may happen physically, but contributions can be made through mobile money or bank channels. Chama Software Thika can provide a central record so that physical meetings and digital transactions do not have to be managed as separate systems.
Why chamas need better records
Good records are not simply an administrative convenience. They help members understand how group money is being handled. When contribution histories are clear, the treasurer spends less time answering repeated questions and the secretary can prepare reports more efficiently. Chama Software Thika can support this transparency by keeping member profiles, contribution entries, loan information and financial summaries organized.
Manual records also create room for simple errors. A figure can be copied incorrectly from one notebook to another, a payment can be entered under the wrong member, or an old spreadsheet can be mistaken for the current version. These problems do not automatically mean that a group is poorly managed; they are common risks when several people maintain records manually. Chama Software Thika can reduce duplicated data entry and create a clearer audit trail.
Another challenge is continuity. Chama officials change over time. A treasurer who has kept detailed personal records may leave the group, making handover difficult. A structured system gives the next official a clearer starting point. Chama Software Thika can make institutional knowledge less dependent on one person’s notebook, phone or spreadsheet.
What chama software should manage
A useful system should begin with the core activities of the group. At minimum, officials should be able to maintain a member register, define contribution rules, record payments, monitor balances and generate reports. Chama Software Thika should also make it easier to separate different financial activities so that savings, welfare, loans and investments are not mixed together.
Member registration and profiles
Every member should have a reliable profile containing the information the group actually needs. Depending on the group’s policies, this could include the member’s name, contact details, membership date, contribution category and status. Chama Software Thika can help officials retrieve member information quickly instead of searching through several notebooks.
Member records should be kept simple. A chama does not need to collect unnecessary personal information simply because software makes it possible. The group should define what information is needed for administration, reporting and accountability, and limit access according to responsibilities. Chama Software Thika should support practical record keeping without turning a savings group into a complicated data-entry exercise.
Contributions and savings
Contribution tracking is usually at the heart of chama administration. The system should allow officials to record regular contributions, identify unpaid amounts and view a member’s contribution history. Chama Software Thika can make it easier to answer questions such as how much a member has contributed during a particular period and whether a payment has been recorded against the correct account.
Different groups use different contribution rules. One chama might require a fixed monthly amount, while another may allow varying amounts or separate savings categories. A group could also have welfare contributions alongside investment savings. Chama Software Thika should therefore be configurable enough to represent the group’s actual contribution structure instead of assuming that every member pays the same amount for the same purpose.
Loan management
Many chamas provide loans to members from pooled funds. Loan administration can become complicated when the group has different limits, repayment periods, interest rules, guarantor requirements or penalties. Chama Software Thika can help officials record applications, approvals, disbursements, repayments and outstanding balances.
A useful loan module should show the status of each loan clearly. Officials should be able to distinguish an approved application from a disbursed loan and a fully repaid facility. Chama Software Thika can also support repayment tracking so that the group has a consistent history for each borrower rather than relying on separate handwritten calculations.
Welfare management
Welfare contributions require a different type of record because the purpose is usually support rather than investment. A group may have rules for contributions and assistance relating to bereavement, illness, emergencies or other agreed situations. Chama Software Thika can keep welfare records separate from ordinary savings, making it easier to understand how the welfare fund is performing.
Clear welfare records can also reduce misunderstandings. Members can see that welfare funds are governed by agreed rules rather than being mixed into general group finances. Chama Software Thika should allow the group to document the relevant transaction and maintain an appropriate history without making sensitive situations unnecessarily public.
M-Pesa and payment records
Mobile money is an important part of everyday financial activity in Kenya, so a chama management system should fit the way members actually pay. A group may receive contributions through M-Pesa, bank transfers or cash during meetings. Chama Software Thika can help officials maintain a consistent record regardless of the payment channel used.
The key issue is reconciliation. Receiving a payment is one step; correctly assigning it to the right member and contribution category is another. Chama Software Thika can support a workflow in which officials verify payment information, record the transaction and update the member’s balance.
A group should also establish clear internal controls around payment confirmation. Software does not remove the need for responsible financial procedures. Officials should agree who records transactions, who verifies them and who reviews reports. Chama Software Thika can make those responsibilities easier to document because the records are organized within a shared system.
Reporting and financial visibility
Reports are useful when they answer real management questions. A chairperson may want to know the group’s overall contribution position. A treasurer may need a detailed transaction report. A member may want to see their own payment history. Chama Software Thika should make it possible to generate information for each of these purposes without manually rebuilding the numbers.
Useful reports can include contribution summaries, member balances, loan outstanding reports, repayment histories, welfare activity and investment records. Chama Software Thika can help officials prepare meeting reports faster, particularly when the same information is requested repeatedly.
Reports should also be understandable. A system can contain sophisticated calculations and still be unhelpful if ordinary members cannot understand the resulting figures. Chama Software Thika should present important information in clear tables or summaries so that a group can discuss its finances during meetings with less confusion.
Meeting management and member communication
Chamas depend on meetings because members make decisions together. Software should therefore support the administrative work around meetings rather than replacing the group’s governance process. Chama Software Thika can help officials prepare information before a meeting, review outstanding contributions and organize reports for discussion.
Communication is another practical concern. Members may need reminders about meetings, contributions or loan repayments. Chama Software Thika can complement existing communication channels by ensuring that reminders are based on current records rather than manually maintained lists.
The group should still decide which communication method is appropriate for each situation. A formal financial report may be shared differently from a simple meeting reminder. Chama Software Thika should support organized administration while leaving the group’s communication policies in the hands of its members and officials.
Transparency and accountability
Trust is one of the most important assets of a chama. Members contribute money because they expect agreed rules to be followed and records to be maintained. Chama Software Thika can strengthen accountability by making financial activity easier to document and review.
Transparency does not mean giving every member unrestricted access to every administrative function. Different roles can have different responsibilities. A treasurer may enter financial transactions, while a chairperson may review reports and ordinary members may view information relevant to their own accounts. Chama Software Thika should support role-based access where appropriate.
An audit trail is also valuable. If a transaction is corrected, the group should be able to understand what changed and why. Chama Software Thika can be part of an internal control framework that encourages consistent recording and review rather than depending entirely on memory.
Security and data protection
Financial records deserve careful handling. Chamas should consider who can access member details, contribution records, loan information and reports. Chama Software Thika should be used alongside sensible password practices, controlled user permissions and clear procedures for officials.
Security is not only a technical issue. A group should also consider operational security. Shared passwords, unattended devices and unofficial copies of financial spreadsheets can expose information. Chama Software Thika can reduce the need for scattered files, but members should still follow responsible access practices.
Backups are another important consideration. A chama should understand how its records are backed up and how information can be recovered if a device is lost or an account becomes inaccessible. Chama Software Thika should form part of a broader continuity plan so that the group’s history is protected.
How a Thika chama can move from manual records to software
Switching systems does not need to happen overnight. A group can start by documenting its current process. List the contribution categories, loan rules, welfare rules, membership requirements and reporting needs. Chama Software Thika can then be configured around those requirements rather than forcing the group to change everything at once.
Step 1: Review existing records
Collect the latest member register, contribution records, loan schedules and other documents. Identify duplicate or conflicting entries before importing information. Chama Software Thika is only as useful as the information entered into it, so data cleanup should be treated as part of the implementation process.
Step 2: Agree on rules
The committee should confirm the rules that the system needs to reflect. This includes contribution frequency, loan limits, repayment terms, penalties, approval procedures and reporting responsibilities. Chama Software Thika should mirror approved group policies, not create policies without the members’ agreement.
Step 3: Assign responsibilities
Decide who will administer the system and who will review financial information. Chama Software Thika works best when responsibilities are clear. The group can define who records payments, who approves loans, who prepares reports and who checks the records.
Step 4: Train users
Training should focus on the tasks officials perform regularly. Demonstrate how to add a member, record a contribution, process a loan repayment and generate a report. Chama Software Thika becomes much easier to adopt when users understand the few workflows they need every week.
Step 5: Start with the essentials
A group does not need to activate every possible feature immediately. Begin with member records and contribution tracking, then introduce loans, welfare, reporting and other functions as the committee becomes comfortable. Chama Software Thika should simplify the group’s routine instead of creating a second layer of administration.
Choosing software for a chama in Thika
There is no single feature that determines whether a chama system is suitable. The right choice depends on the group’s size, financial activities, technical comfort and reporting needs. Chama Software Thika should be evaluated against actual day-to-day tasks rather than impressive feature lists.
Ease of use
If a treasurer needs advanced technical skills to record a contribution, adoption will suffer. Chama Software Thika should have a straightforward interface and workflows that make sense to people who are not software specialists.
Scalability
A group may start with twenty members and later grow. It may also expand from simple savings into loans or investments. Chama Software Thika should be capable of supporting increased activity without forcing the group to replace its records every time its operations change.
Reporting
Ask for examples of the reports the system can produce. Chama Software Thika should support the reports the committee actually uses, including contribution summaries, loan balances and transaction histories where relevant.
Support
Technical support matters when users encounter a problem. Before adopting Chama Software Thika, a group should understand how support is provided, what channels are available and what happens when an urgent issue affects financial administration.
Cost considerations
Software pricing should be assessed against the value and administrative time saved. A low-cost system can still be unsuitable if it lacks important features, while an expensive platform may contain capabilities a small group will never use. Chama Software Thika should be evaluated using the group’s real requirements and budget.
Common mistakes when digitizing a chama
One mistake is buying software before agreeing on internal rules. If members disagree about contribution categories or loan procedures, technology will not resolve the underlying governance issue. Chama Software Thika should document agreed processes rather than becoming a substitute for decision-making.
Another mistake is entering incomplete historical data. A group may upload only current balances without retaining enough transaction history to explain them. Chama Software Thika is more useful when the group decides what historical information needs to be preserved and verifies opening balances.
A third mistake is giving too many people administrative access. More access does not necessarily mean more transparency. Chama Software Thika should be configured so that people have the access required for their responsibilities and no more.
Groups can also make the mistake of treating software as an automatic accounting solution without review. Chama Software Thika can organize records and calculations, but officials should still reconcile balances, review reports and investigate discrepancies.
Practical example: a Thika investment chama
Consider a group of members who meet monthly in Thika and contribute money toward long-term investments. Before using software, the treasurer records payments in a notebook, calculates balances with a calculator and sends a summary in a WhatsApp group. When a member asks about their total contribution, the treasurer searches through several pages.
With Chama Software Thika, the group can maintain a member register and record each contribution against the relevant account. At the monthly meeting, officials can generate a contribution summary and discuss the group’s financial position using the same records.
If the group later issues a member loan, the loan can be recorded separately from investment contributions. Chama Software Thika can help officials follow the loan from approval to repayment while preserving the contribution history.
The example shows why the value of software is not simply replacing paper. The larger benefit is creating a repeatable process. Chama Software Thika can give the group a common record that supports routine administration, reporting and handover between officials.
Practical example: a welfare chama
A welfare group may collect a smaller regular contribution but make occasional support payments. Its needs are different from those of an investment group. Chama Software Thika can help maintain separate records for contributions and approved welfare disbursements.
Suppose the committee reviews welfare activity at the end of a quarter. Instead of reconstructing the information from receipts and messages, officials can use the system’s records to prepare a summary. Chama Software Thika can make the discussion more focused because the committee can spend less time assembling basic figures.
The group can also define who is authorized to approve welfare support. Chama Software Thika should support the administrative trail around those decisions while the actual approval remains governed by the group’s constitution or agreed rules.
Practical example: a chama with member loans
Loan-based chamas need particular attention to balances. A member may borrow funds, make partial repayments and then request an updated statement. Chama Software Thika can help keep the original loan details and subsequent repayments connected.
The committee can also use reports to identify outstanding balances. Chama Software Thika can reduce the risk of relying on isolated handwritten calculations, especially when several members have active loans at the same time.
The group should still establish clear lending rules. Software cannot decide whether a particular member should receive a loan unless the group has already defined its eligibility and approval process. Chama Software Thika provides an administrative framework for those rules.
Benefits for different chama officials
A chairperson often needs a high-level view. Chama Software Thika can help the chairperson access organized summaries for meetings and oversight without requiring them to inspect every individual transaction.
A treasurer needs detailed transaction management. Chama Software Thika can help the treasurer record contributions, track loan repayments and prepare financial reports.
A secretary may focus on membership and meeting administration. Chama Software Thika can help keep member information and routine records organized.
Ordinary members benefit from clearer information about their own contributions and obligations. Chama Software Thika can support member confidence when records are maintained consistently and reports are available according to the group’s access rules.
How software can support growth
Growth changes administrative needs. A group that once handled ten or fifteen transactions a month may eventually process many more. Chama Software Thika can help the group maintain a consistent process as transaction volume increases.
Expansion can also introduce new categories. A chama might begin with savings, add welfare contributions, introduce member loans and later invest in property. Chama Software Thika should be able to accommodate those changes without making the original records unusable.
The group should review its system periodically. Chama Software Thika may continue to be suitable, but requirements can change as membership, financial activity and governance arrangements develop.
Questions to ask before choosing a system
Before making a decision, a committee can ask:
- Can the system maintain individual member records?
- Can it record recurring contributions?
- Can it track outstanding balances?
- Does it support loans and repayments if the group offers loans?
- Can welfare transactions be separated from other funds?
- Can reports be generated for meetings?
- What user roles and permissions are available?
- How are records backed up?
- What support is available when users need help?
- What are the total costs of using the system?
These questions help the committee compare practical capabilities instead of relying on marketing language. Chama Software Thika should be assessed against the answers and the group’s documented requirements.
Why local context matters
A software platform should fit the way Kenyan groups actually operate. Mobile payments, physical meetings, local business activity and member communication patterns all affect chama administration. Chama Software Thika should make those everyday processes easier rather than requiring members to build complicated workarounds.
For a chama operating around Thika, the system should also accommodate members who may live or work in nearby towns. A member may attend meetings irregularly because of work, yet still need their contribution and loan records updated accurately. Chama Software Thika can help centralize information so that physical attendance is not the only way to understand a member’s account.
Local context also means considering connectivity, device access and user experience. Not every official is a technology specialist. Chama Software Thika should therefore be practical enough for routine use by the people responsible for group administration.
Improving financial discipline with better processes
Software cannot create financial discipline by itself. Discipline comes from rules, consistent recording, review and accountability. Chama Software Thika can support those habits by giving officials a structured place to record transactions and prepare reports.
A useful routine might involve recording payments promptly, reconciling them regularly, reviewing outstanding balances before meetings and keeping reports for committee review. Chama Software Thika can fit into that routine and reduce the amount of manual work required.
The group should also agree on what happens when an error is discovered. Instead of silently changing figures, officials should follow an approved correction process. Chama Software Thika can help preserve clearer records when corrections are documented appropriately.
A simple operating model for a Thika chama
Digital tools work best when the group also has a clear operating routine. A committee can create a monthly cycle that makes administration predictable. During the first few days of a new contribution period, members make their payments through the agreed channels. The responsible official records or verifies those payments. Any exceptions are flagged rather than left for the next meeting.
Before the monthly meeting, the treasurer can review the contribution position and outstanding obligations. The secretary can confirm the membership information needed for the agenda, while the chairperson can review reports that require committee attention. This preparation means the meeting begins with information already organized.
During the meeting, members can focus on decisions. They can discuss proposed loans, investment opportunities, welfare requests, budgets or other matters covered by the group’s rules. The records provide supporting information, but they do not replace member discussion or approval.
After the meeting, approved transactions can be recorded promptly. Minutes and financial records should be kept according to the group’s procedures. This creates a useful separation between discussion, approval and recording.
Handling corrections
Every financial system eventually encounters an error. A payment may be entered twice, a member may use an incorrect reference, or an amount may be assigned to the wrong category. The solution should be a documented correction process rather than informal editing.
The committee can define who is allowed to correct transactions and what evidence is required. For example, an official may need to confirm a payment reference before changing a member’s contribution record. A second official can review significant corrections. This creates accountability without making simple administration unnecessarily slow.
Preparing for leadership handover
Leadership changes are normal in member organizations. A good handover should cover user access, current balances, outstanding loans, pending transactions, reports and any unresolved issues. It should not depend on one official explaining everything from memory.
A structured digital record can make this process easier. The incoming treasurer can learn the standard workflow, review historical information and understand current obligations. The outgoing treasurer can focus on explaining exceptional matters rather than teaching the successor how every ordinary transaction has been recorded.
Keeping members informed
Members do not all need the same level of technical detail. Some may want a simple contribution balance, while committee members may need transaction-level reports. Communication should therefore be designed around the audience.
A monthly statement can summarize a member’s contributions, outstanding obligations and relevant balances. A committee report can provide a wider view of group finances. A management report can highlight arrears, loan performance or other matters requiring action.
Clear communication also helps prevent small questions from becoming major disputes. When members can understand how their records were calculated and officials can refer to a consistent source, conversations become easier to resolve.
Costs, value and return on administrative effort
Cost should be considered, but it should not be the only question. A committee should also consider the time currently spent maintaining records. If officials spend several hours every month calculating balances, preparing statements and checking duplicated entries, those hours have an administrative cost.
A practical evaluation can compare the current process with the proposed digital process. List the recurring tasks, estimate how often they occur and identify where delays or errors happen. Then determine whether the software addresses those specific problems.
The group should also consider predictable and less obvious costs. These can include setup, training, payment-related charges where applicable, additional users, support arrangements or migration of historical records. The exact cost structure varies between providers, so the committee should request current pricing before making a decision.
Value can also come from better visibility. If a committee can identify unpaid contributions earlier, prepare reports faster or follow loan balances more consistently, the system may save more than direct administrative expenses. Those benefits should be assessed using the group’s own experience rather than generic claims.
A checklist for committee approval
Before adopting a platform, the committee can prepare a short approval checklist:
- Member records can be maintained accurately.
- Contribution categories match the group’s rules.
- Loan features reflect the group’s lending process where loans are offered.
- Welfare records can be separated where necessary.
- Reports support monthly and annual reviews.
- Payment records can be reconciled using the group’s chosen channels.
- User permissions are appropriate.
- Backup and recovery arrangements are understood.
- Support contacts and response expectations are clear.
- Pricing is understood before implementation.
- Existing data can be migrated or entered without creating unexplained balances.
- Officials have enough training to perform routine tasks.
- Members understand what information they can access.
- The committee has a process for reviewing the system after implementation.
This checklist can be used during demonstrations. Instead of asking whether a provider has a long list of features, officials can ask the provider to demonstrate the exact tasks the chama performs. That approach gives the committee a more realistic picture of usability.
What success should look like after implementation
Success should be measurable in practical terms. Within the first few months, officials should be able to identify whether routine record keeping has become easier. They should know whether reports take less time to prepare, whether contribution records are easier to reconcile and whether members have fewer unanswered questions about their balances.
Adoption is another useful measure. If officials continue keeping parallel notebooks because they do not trust or understand the new system, the implementation has not fully succeeded. Training, workflow adjustments and clearer responsibilities may be needed.
Data quality is equally important. The group can periodically compare selected records against supporting payment evidence and meeting records. This does not need to become a burdensome audit; a regular review can catch small issues before they accumulate.
Finally, the committee should ask members whether the information they receive is clearer. A digital system should support trust through better organization, not simply produce more screens and reports.
Building a sustainable digital chama
A chama’s needs may change over time. Membership can increase, contribution amounts can change, a new loan product can be introduced, or an investment project can create new reporting requirements. The system should therefore be reviewed periodically.
The committee can schedule a simple annual technology review. Discuss what works, what creates friction, which reports are useful and what new requirements have emerged. If the current platform continues to meet those needs, the group can maintain it. If important gaps have appeared, the committee can investigate alternatives based on documented requirements.
The most sustainable approach is usually the simplest one that reliably supports the group’s operations. A committee should avoid introducing features merely because they exist. Every function adds some level of training, administration or governance responsibility.
A digital chama is ultimately still a member organization. Technology can organize information, calculate balances, generate reports and support communication, but members remain responsible for the decisions that shape the group. Good governance, transparent rules and consistent financial controls should remain at the center of the process.
For a group in Thika, that combination can create a practical path from informal record keeping to organized digital administration. The objective is not to make the chama feel like a large corporation. It is to give ordinary members and officials reliable information they can use when managing their shared financial activities.
Frequently asked questions
What is chama software?
Chama software is a digital management system designed to organize activities such as member registration, savings, contributions, loans, welfare funds, reporting and group administration. Chama Software Thika can replace or reduce dependence on notebooks and disconnected spreadsheets.
Is chama software useful for small groups?
Yes, if the system matches the group’s needs. A small group can benefit from organized contribution records and easier reporting, but it should avoid paying for complex functions it does not need. Chama Software Thika should be selected according to the group’s size, activities and budget.
Can a chama use software to track M-Pesa payments?
A system can be used to record and reconcile payments made through mobile money, depending on the platform’s payment capabilities and configuration. Chama Software Thika should be evaluated specifically for the payment workflow the group intends to use.
Can software manage chama loans?
Many chama management platforms provide loan-related functionality, but features differ. Chama Software Thika should be checked for the group’s specific requirements, including applications, approvals, disbursements, repayment schedules, interest calculations and outstanding balances.
How does software improve chama transparency?
It can create organized records, standardized reports and clearer transaction histories. Chama Software Thika can support transparency when the group also has appropriate approval procedures, access controls and regular financial reviews.
Is chama software suitable for investment groups in Thika?
It can be, provided it supports the group’s actual investment and financial administration needs. Chama Software Thika should be evaluated for contribution tracking, member records, reporting, loans where applicable and the way the group documents investments.
What should a chama do before moving to digital records?
The committee should review existing records, agree on rules, clean up inconsistent information and assign administrative responsibilities. Chama Software Thika should then be configured around those agreed processes.
How many people should have administrative access?
There is no universal number. Access should reflect responsibilities and internal controls. Chama Software Thika should allow the group to limit sensitive functions to authorized officials while giving members appropriate visibility into their own records.
Can software replace chama meetings?
No. Software can support administration and reporting, but group meetings remain important for decisions governed by the chama’s constitution and agreed rules. Chama Software Thika should support those meetings by making relevant information easier to prepare and review.
What makes a chama system easy to use?
Clear navigation, simple data entry, useful reports and workflows that match the group’s actual processes all contribute to usability. Chama Software Thika should make routine tasks easier rather than adding unnecessary administrative steps.
Final considerations for chamas in Thika
A well-managed chama depends on more than collecting money. Members need reliable records, clear rules, responsible officials and timely information. Chama Software Thika can provide the digital structure that connects those elements, particularly when a group has outgrown notebooks or scattered spreadsheets.
The best starting point is to map the group’s current workflow. Identify how members join, how contributions are collected, how loans are approved, how welfare support is handled, how meetings are prepared and how financial reports are reviewed. Chama Software Thika should then be assessed against those requirements.
For groups in Thika, the practical objective is straightforward: reduce avoidable administrative work while improving the consistency and visibility of financial records. Chama Software Thika can support that objective when it is implemented carefully and used alongside sound governance.
Before choosing a platform, compare features, user roles, reporting capabilities, payment workflows, support arrangements, security practices and total cost. Chama Software Thika should be judged by whether it solves the group’s actual problems rather than by the number of features listed on a sales page.
A chama that adopts software successfully does not simply become more digital. It develops a more consistent way to record activity, prepare information and hand responsibilities from one official to another. Chama Software Thika can be part of that transition, giving members and committee officials a clearer view of the group’s day-to-day administration.
For a growing savings, welfare or investment group in Thika, the decision to digitize should therefore begin with the group’s needs. Chama Software Thika can provide the technology, but the members’ rules, accountability practices and financial decisions remain the foundation of a healthy chama.
When the technology is aligned with those foundations, Chama Software Thika can help turn repetitive administrative tasks into a more organized workflow. The result is not merely faster record keeping; it is a group that can spend more meeting time discussing decisions and less time reconstructing figures.
The next step for any committee is to document its requirements, review suitable systems and test the workflows that matter most. Chama Software Thika should pass that practical test before the group commits to implementation.
For chamas that are ready to move beyond manual records, the goal is not complicated technology. It is dependable administration. Chama Software Thika can help make member records, contributions, loans, welfare activity and reports easier to manage when the system is selected and configured around the group’s real operations.